Owning a home has great financial benefits.
In a recent research paper, Homeownership and the American Dream, Laurie S. Goodman and Christopher Mayer of the Urban Land Institute explained:
“Homeownership appears to help borrowers accumulate housing and nonhousing wealth in a variety of ways, with tax advantages, greater financial flexibility due to secured borrowing, built-in ‘default’ savings with mortgage amortization and nominally fixed payments, and the potential to lower home maintenance costs through sweat equity.”
Let’s breakdown 5 major financial benefits of homeownership:
1. Housing is typically the one leveraged investment available
Homeownership allows households to amplify any appreciation on the value of their homes by a leverage factor. A 20% down payment results in a leverage factor of five, meaning every percentage point rise in the value of your home is a 5% return on your equity. If you put down 10%, your leverage factor is 10.
Example: Let’s assume you purchased a $300,000 home and put down $60,000 (20%). If the house appreciates by $30,000, that is only a 10% increase in value but a 50% increase in equity.
2. You’re paying for housing whether you own or rent
Some argue that renting eliminates the cost of property taxes and home repairs. Every potential renter must realize that all the expenses the landlord incurs (property taxes, repairs, insurance, etc.) are baked into the rent payment already – along with a profit margin!!
3. Owning is usually a form of “forced savings”
Studies have shown that homeowners have a net worth that is 44X greater than that of a renter. As a matter of fact, it was recently estimated that a family buying an average priced home this past January could build more than $42,000 in family wealth over the next five years.
4. Owning is a hedge against inflation
House values and rents tend to go up at or higher than the rate of inflation. When you own, your home’s value will protect you from that inflation.
5. There are still substantial tax benefits to owning
We know that the new tax reform bill puts limits on some deductions on certain homes. However, in the research paper referenced above, the authors explain:
“…the mortgage interest deduction is not the main source of these gains; even if it were removed, homeowners would continue to benefit from a lack of taxation of imputed rent and capital gains.”
Bottom Line
From a financial standpoint, owning a home has always been and will always be better than renting.
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017 & 2018 Recognition of Excellence Award Winner SDAR
Showing posts with label should i rent or buy. Show all posts
Showing posts with label should i rent or buy. Show all posts
Sunday, July 21, 2019

Saturday, August 11, 2018
Buying Is Now 26.3% Cheaper Than Renting in the US
The results of the latest Rent vs. Buy Report from Trulia show that homeownership remains cheaper than renting, with a traditional 30-year fixed rate mortgage, in 98 of the 100 largest metro areas in the United States.
In the six years that Trulia has conducted this study, this is the first time that it was cheaper to rent than buy in any of the metropolitan areas.
It’s no surprise, however, that those two metros are San Jose and San Francisco, CA, where median home prices have jumped to over $1 million dollars this year. Home values in San Jose have risen 29% in the last year, while rents have remained relatively unchanged.
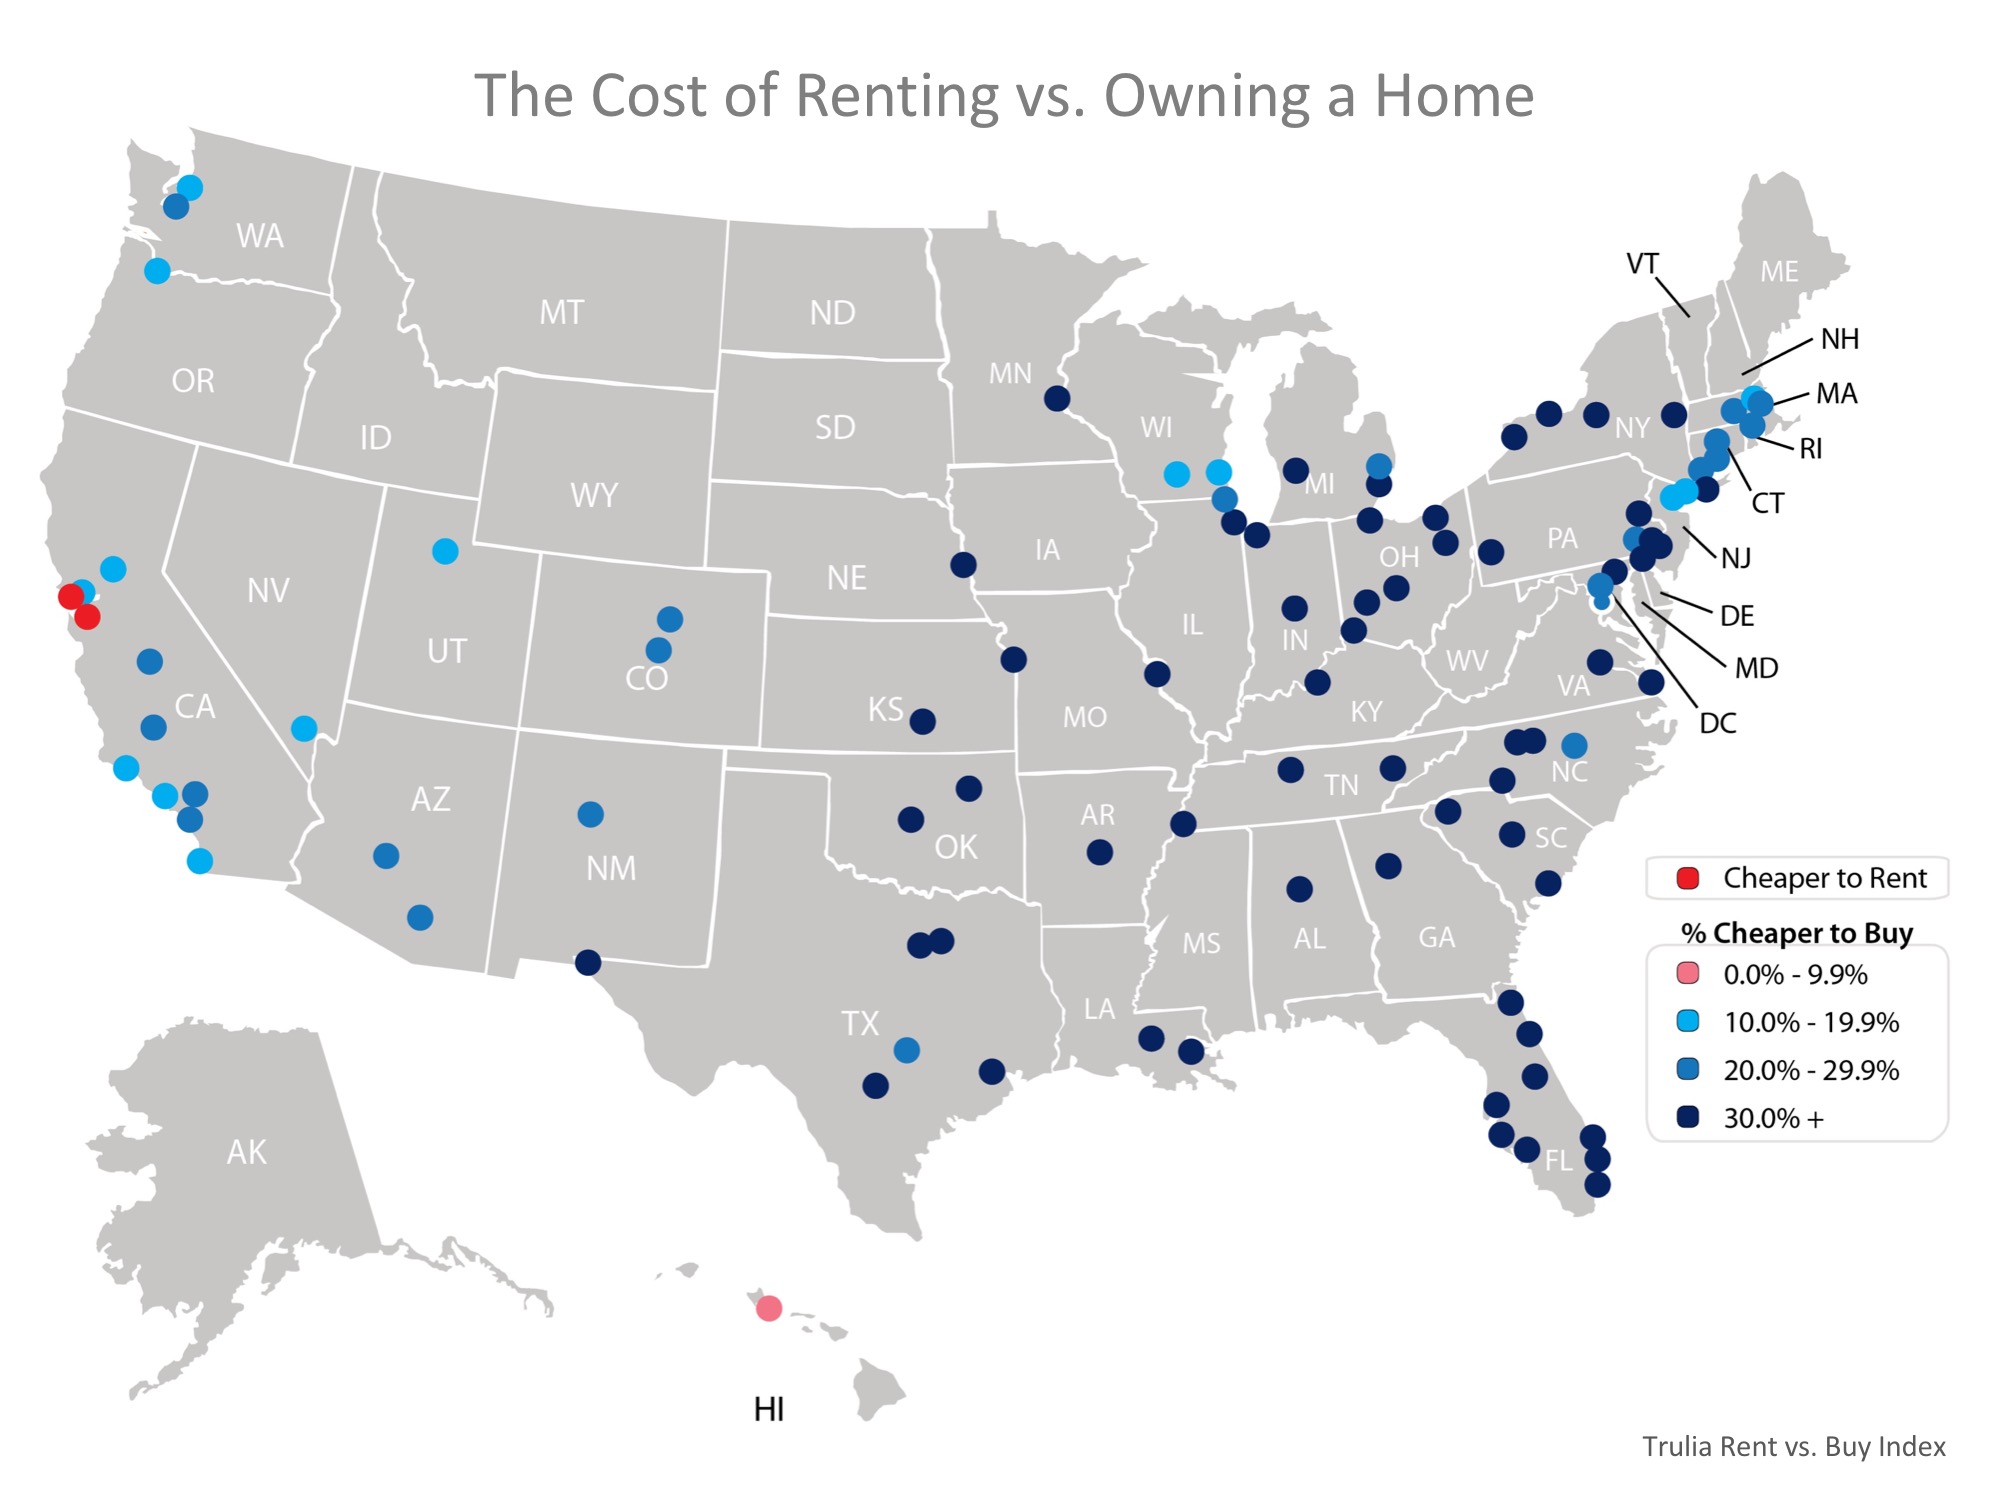
For the 98 metros where homeownership wins out, 97 of them show a double-digit advantage when buying. The range is an average of 2.0% less expensive in Honolulu (HI), all the way up to 48.9% in Detroit (MI), and 26.3% nationwide!
Below is a map of the 100 metros that were studied. The darker the blue dot on the metro, the cheaper it is to buy there.
In order to calculate the true cost of renting vs. buying, Trulia includes all assumed renting costs, including one-time costs (like security deposits), and compares them to the monthly costs of owning a home (insurance, mortgage payments, taxes, and maintenance) including one-time costs (down payments, closing costs, sale proceeds). They also assume that households stay in their home for seven years, put down a 20% down payment, and take out a 30-year fixed rate mortgage. The full methodology is included with the study results here.
Below is a chart created with the data from the last six years of the study, showing the impact of the median home price, rental price, and 30-year fixed rate interest rate used to calculate the ‘cheaper to buy’ metric.
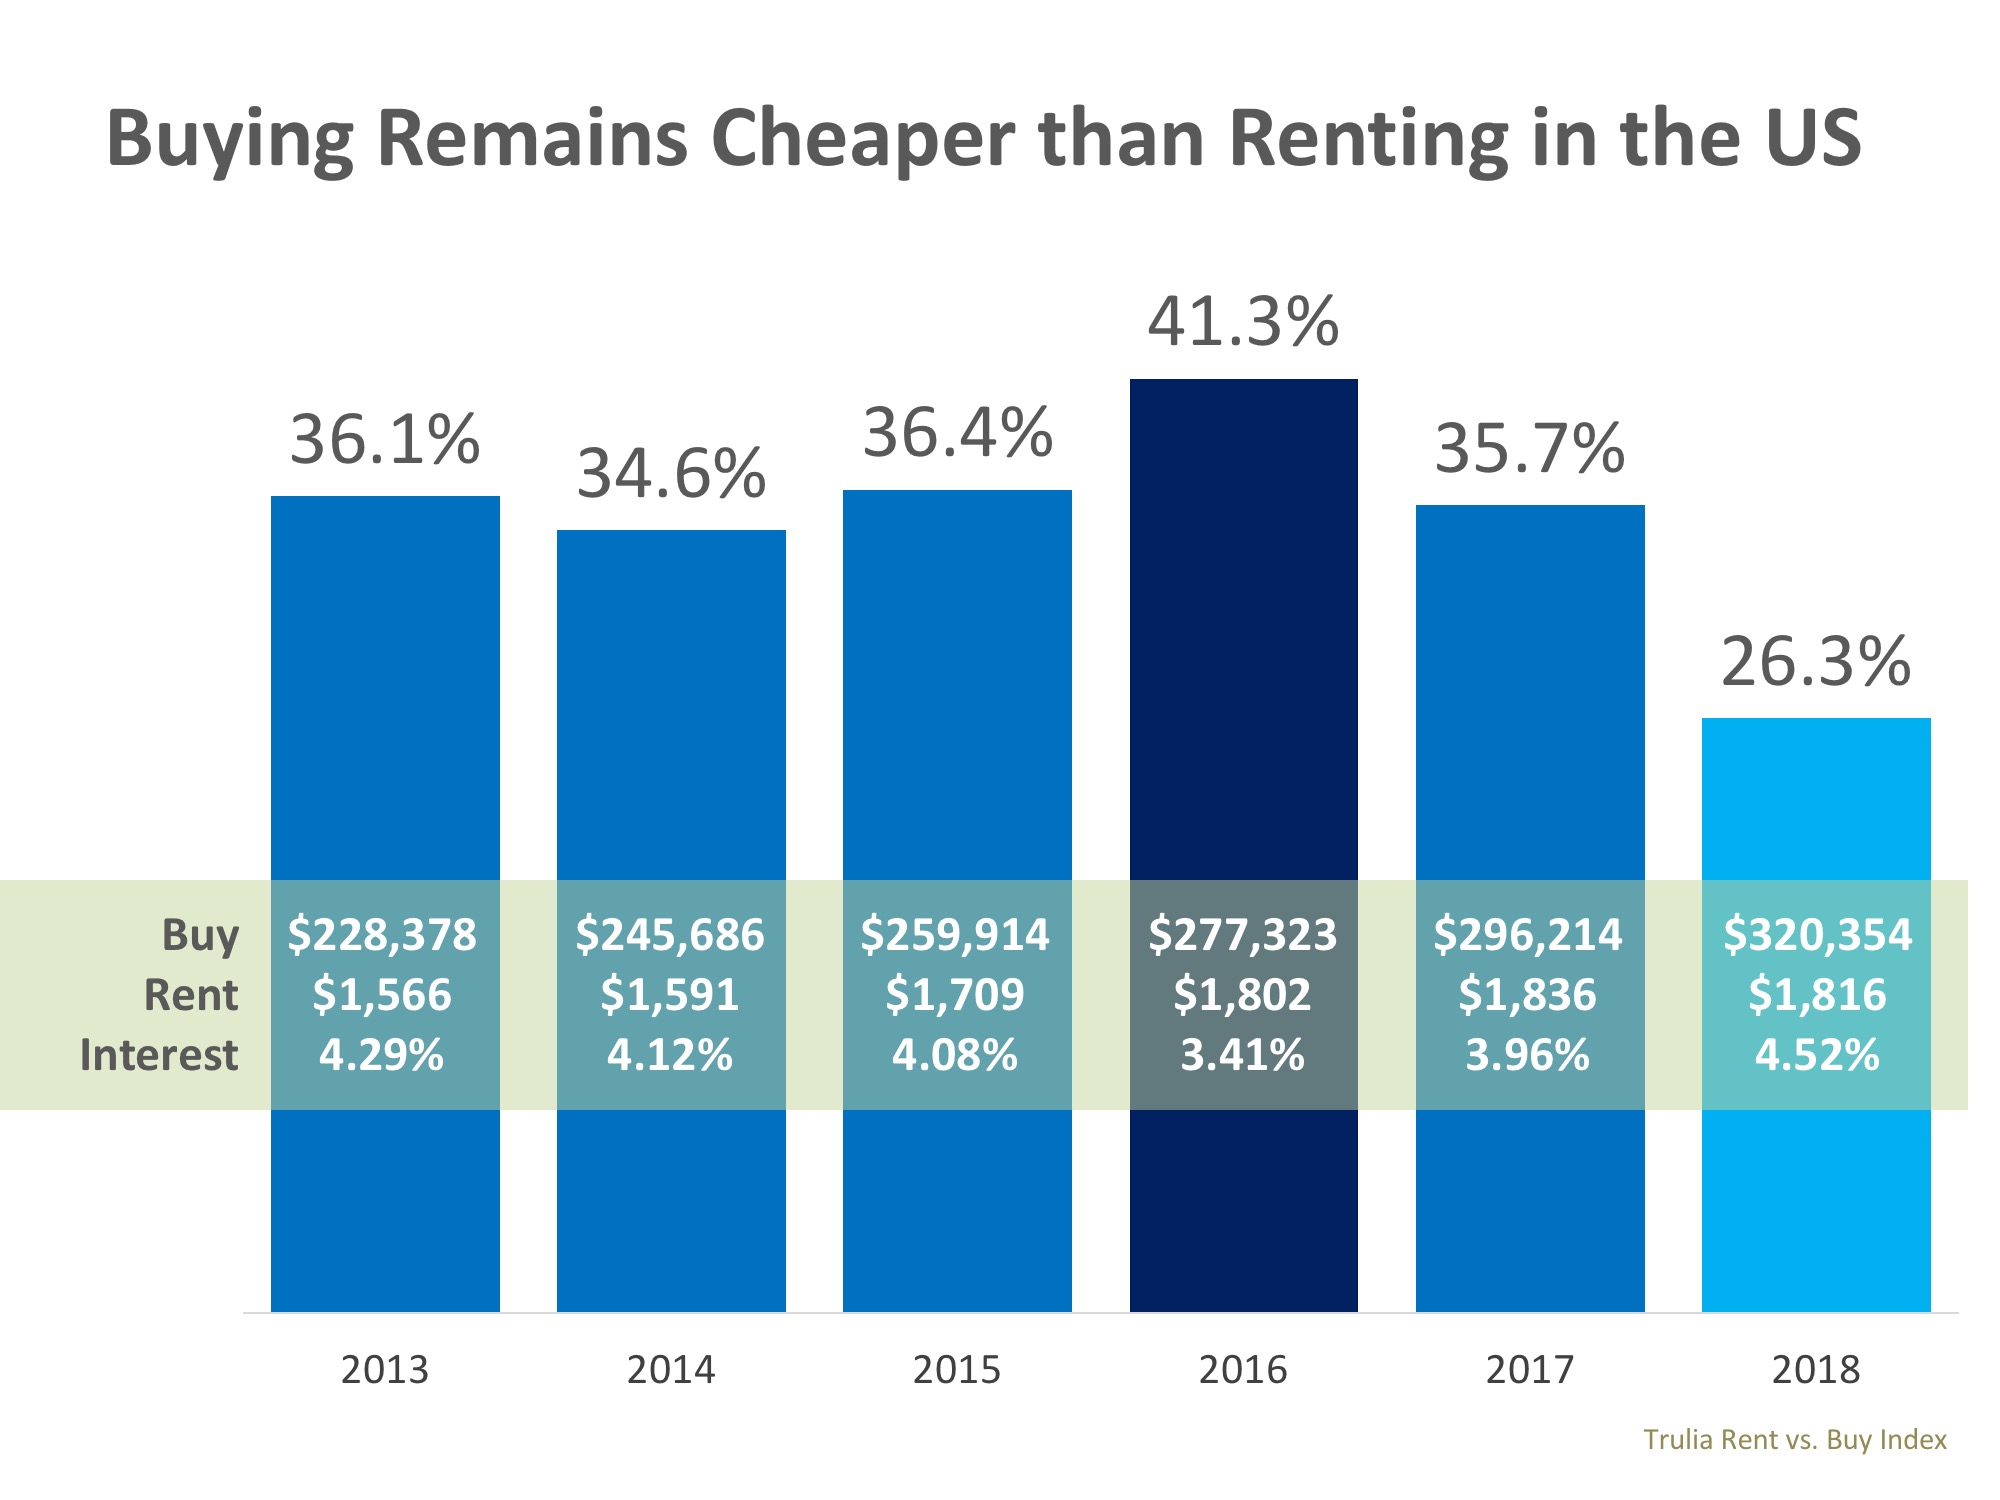
In 2016, when buying was 41.3% less expensive than renting, the average mortgage rate was the driving force behind the difference. Rates this year are the highest they have been in six years which has narrowed the gap, all while home price appreciation has also been driven up by a lack of homes for sale.
Cheryl Young, Trulia’s Chief Economist, had this to say,
“One point deserves emphasizing: The ultra-costly San Francisco Bay Area is not a harbinger for the nation as a whole. While renting may outweigh buying in San Jose and San Francisco, it is unlikely that renting will tip the scales nationally anytime soon.”
Bottom Line
Homeownership provides many benefits beyond the financial ones. If you are one of the many renters out there who would like to evaluate your ability to buy this year, let’s get together to find your dream home.
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 & 2017 Recognition of Excellence Award Winner SDAR
In the six years that Trulia has conducted this study, this is the first time that it was cheaper to rent than buy in any of the metropolitan areas.
It’s no surprise, however, that those two metros are San Jose and San Francisco, CA, where median home prices have jumped to over $1 million dollars this year. Home values in San Jose have risen 29% in the last year, while rents have remained relatively unchanged.
For the 98 metros where homeownership wins out, 97 of them show a double-digit advantage when buying. The range is an average of 2.0% less expensive in Honolulu (HI), all the way up to 48.9% in Detroit (MI), and 26.3% nationwide!
Below is a map of the 100 metros that were studied. The darker the blue dot on the metro, the cheaper it is to buy there.
In order to calculate the true cost of renting vs. buying, Trulia includes all assumed renting costs, including one-time costs (like security deposits), and compares them to the monthly costs of owning a home (insurance, mortgage payments, taxes, and maintenance) including one-time costs (down payments, closing costs, sale proceeds). They also assume that households stay in their home for seven years, put down a 20% down payment, and take out a 30-year fixed rate mortgage. The full methodology is included with the study results here.
Below is a chart created with the data from the last six years of the study, showing the impact of the median home price, rental price, and 30-year fixed rate interest rate used to calculate the ‘cheaper to buy’ metric.
In 2016, when buying was 41.3% less expensive than renting, the average mortgage rate was the driving force behind the difference. Rates this year are the highest they have been in six years which has narrowed the gap, all while home price appreciation has also been driven up by a lack of homes for sale.
Cheryl Young, Trulia’s Chief Economist, had this to say,
“One point deserves emphasizing: The ultra-costly San Francisco Bay Area is not a harbinger for the nation as a whole. While renting may outweigh buying in San Jose and San Francisco, it is unlikely that renting will tip the scales nationally anytime soon.”
Bottom Line
Homeownership provides many benefits beyond the financial ones. If you are one of the many renters out there who would like to evaluate your ability to buy this year, let’s get together to find your dream home.
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 & 2017 Recognition of Excellence Award Winner SDAR
Wednesday, May 23, 2018
Renters Under 50 Want to Buy a Home!
Every year, the New York Federal Reserve publishes the results of their Survey of Consumer Expectations (SCE). Each survey covers a wide range of topics including inflation, labor market, household finance, credit access and housing.
One of the many questions asked in the housing section of the survey was:
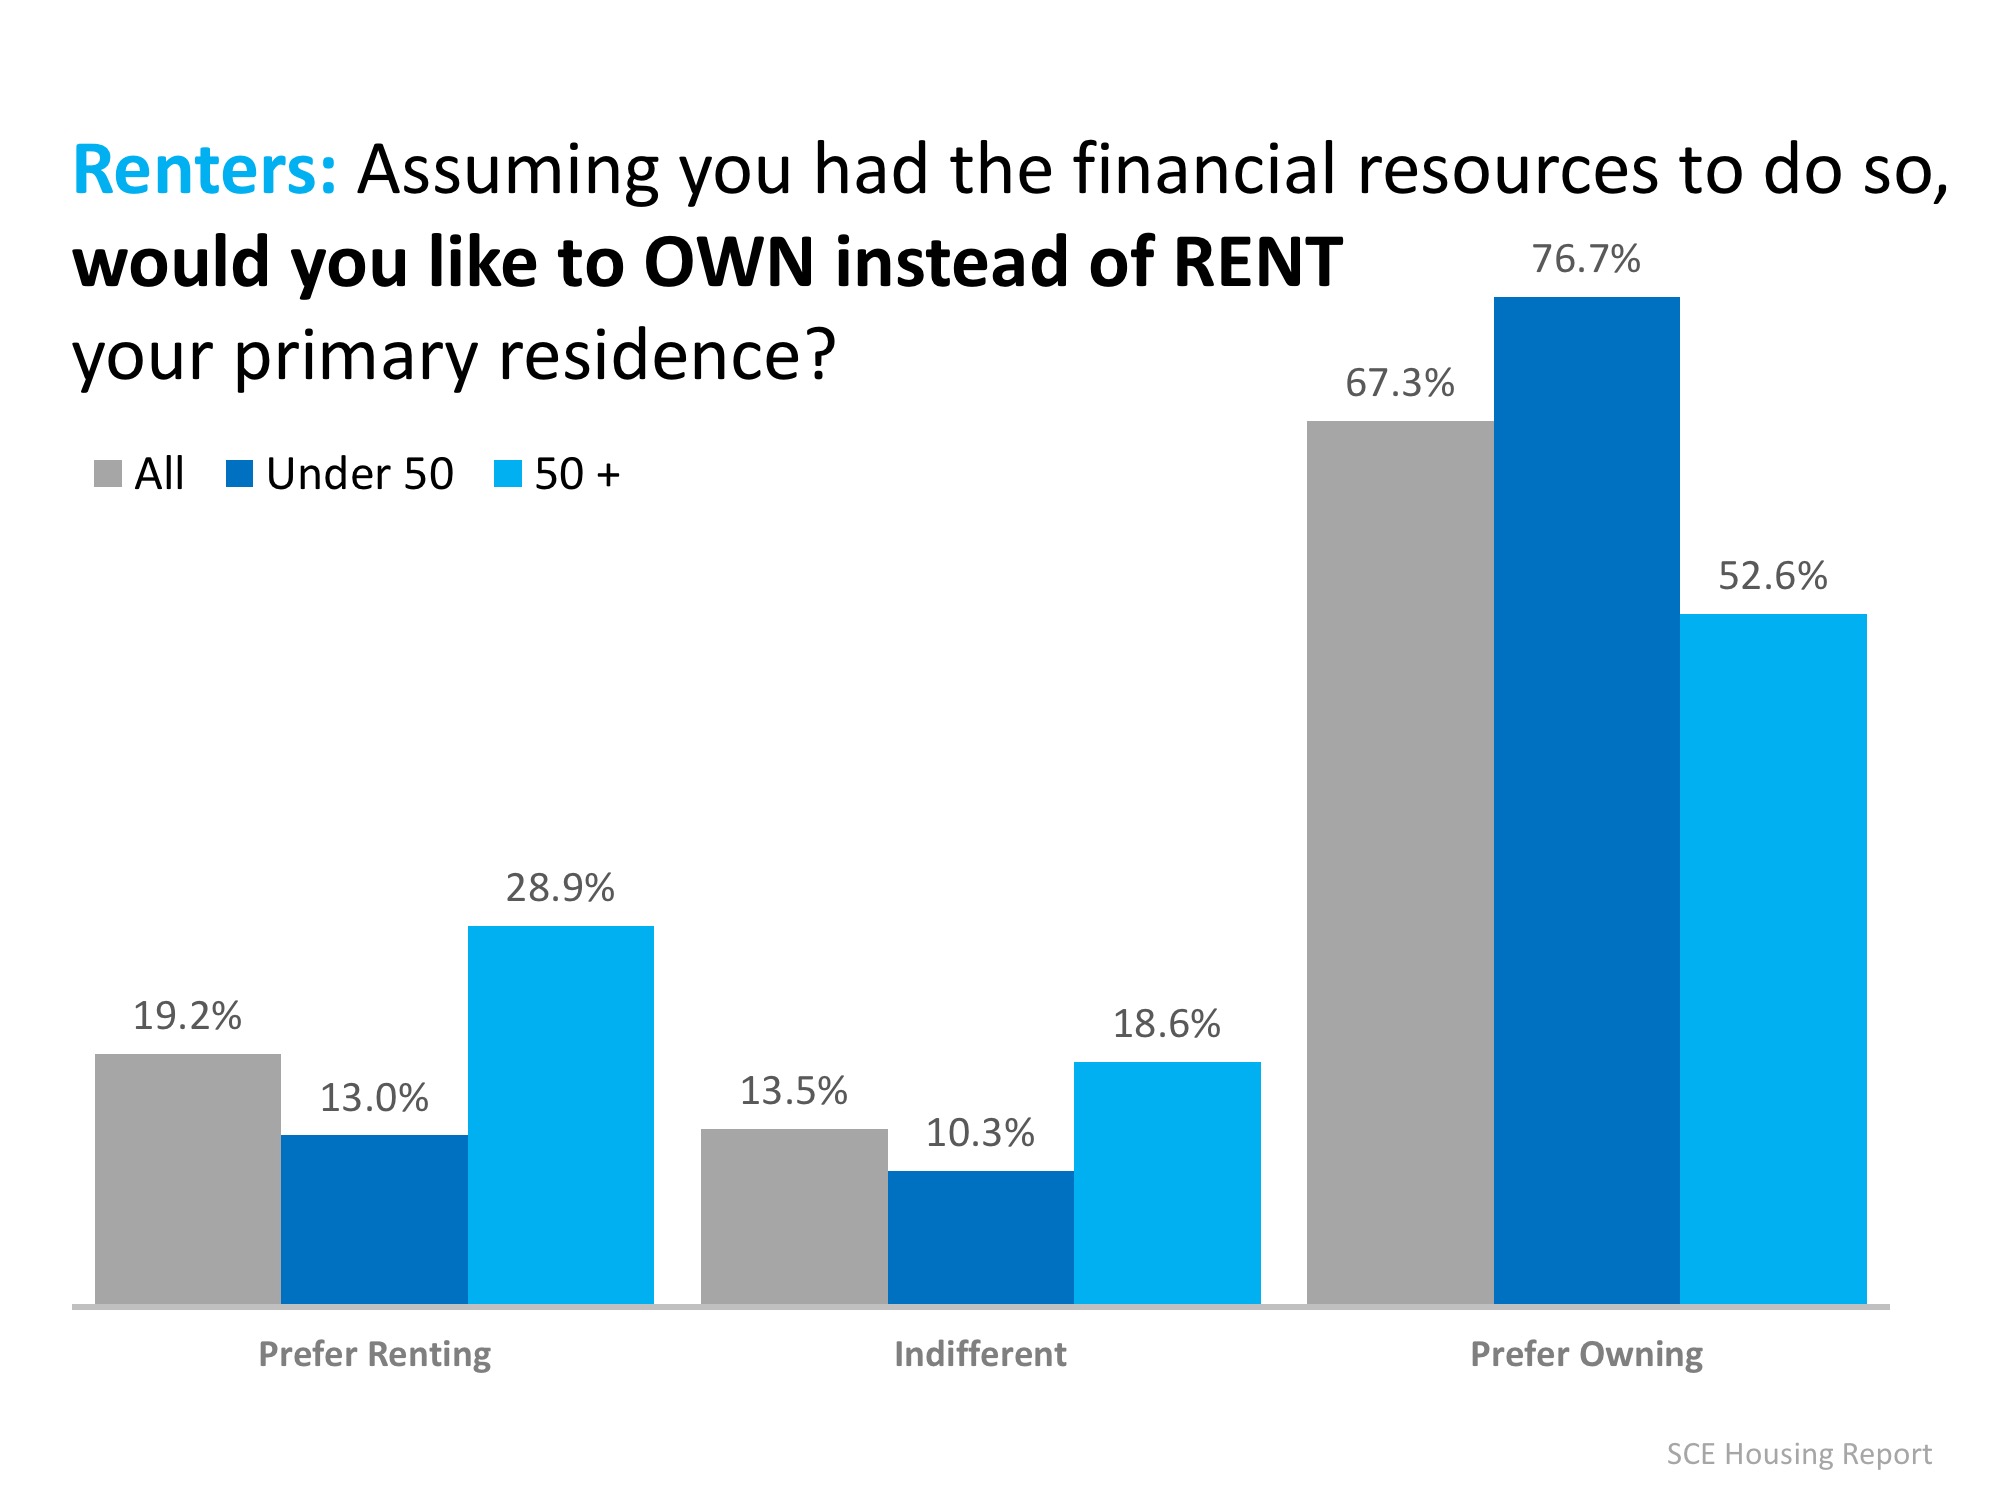
Assuming you had the financial resources to do so, would you like to OWN instead of RENT your primary residence?
Over three-quarters of respondents under the age of 50 said that they would prefer to own their home, rather than rent. While only 52.6% of those over 50 would prefer to own. The full breakdown can be found in the chart below.
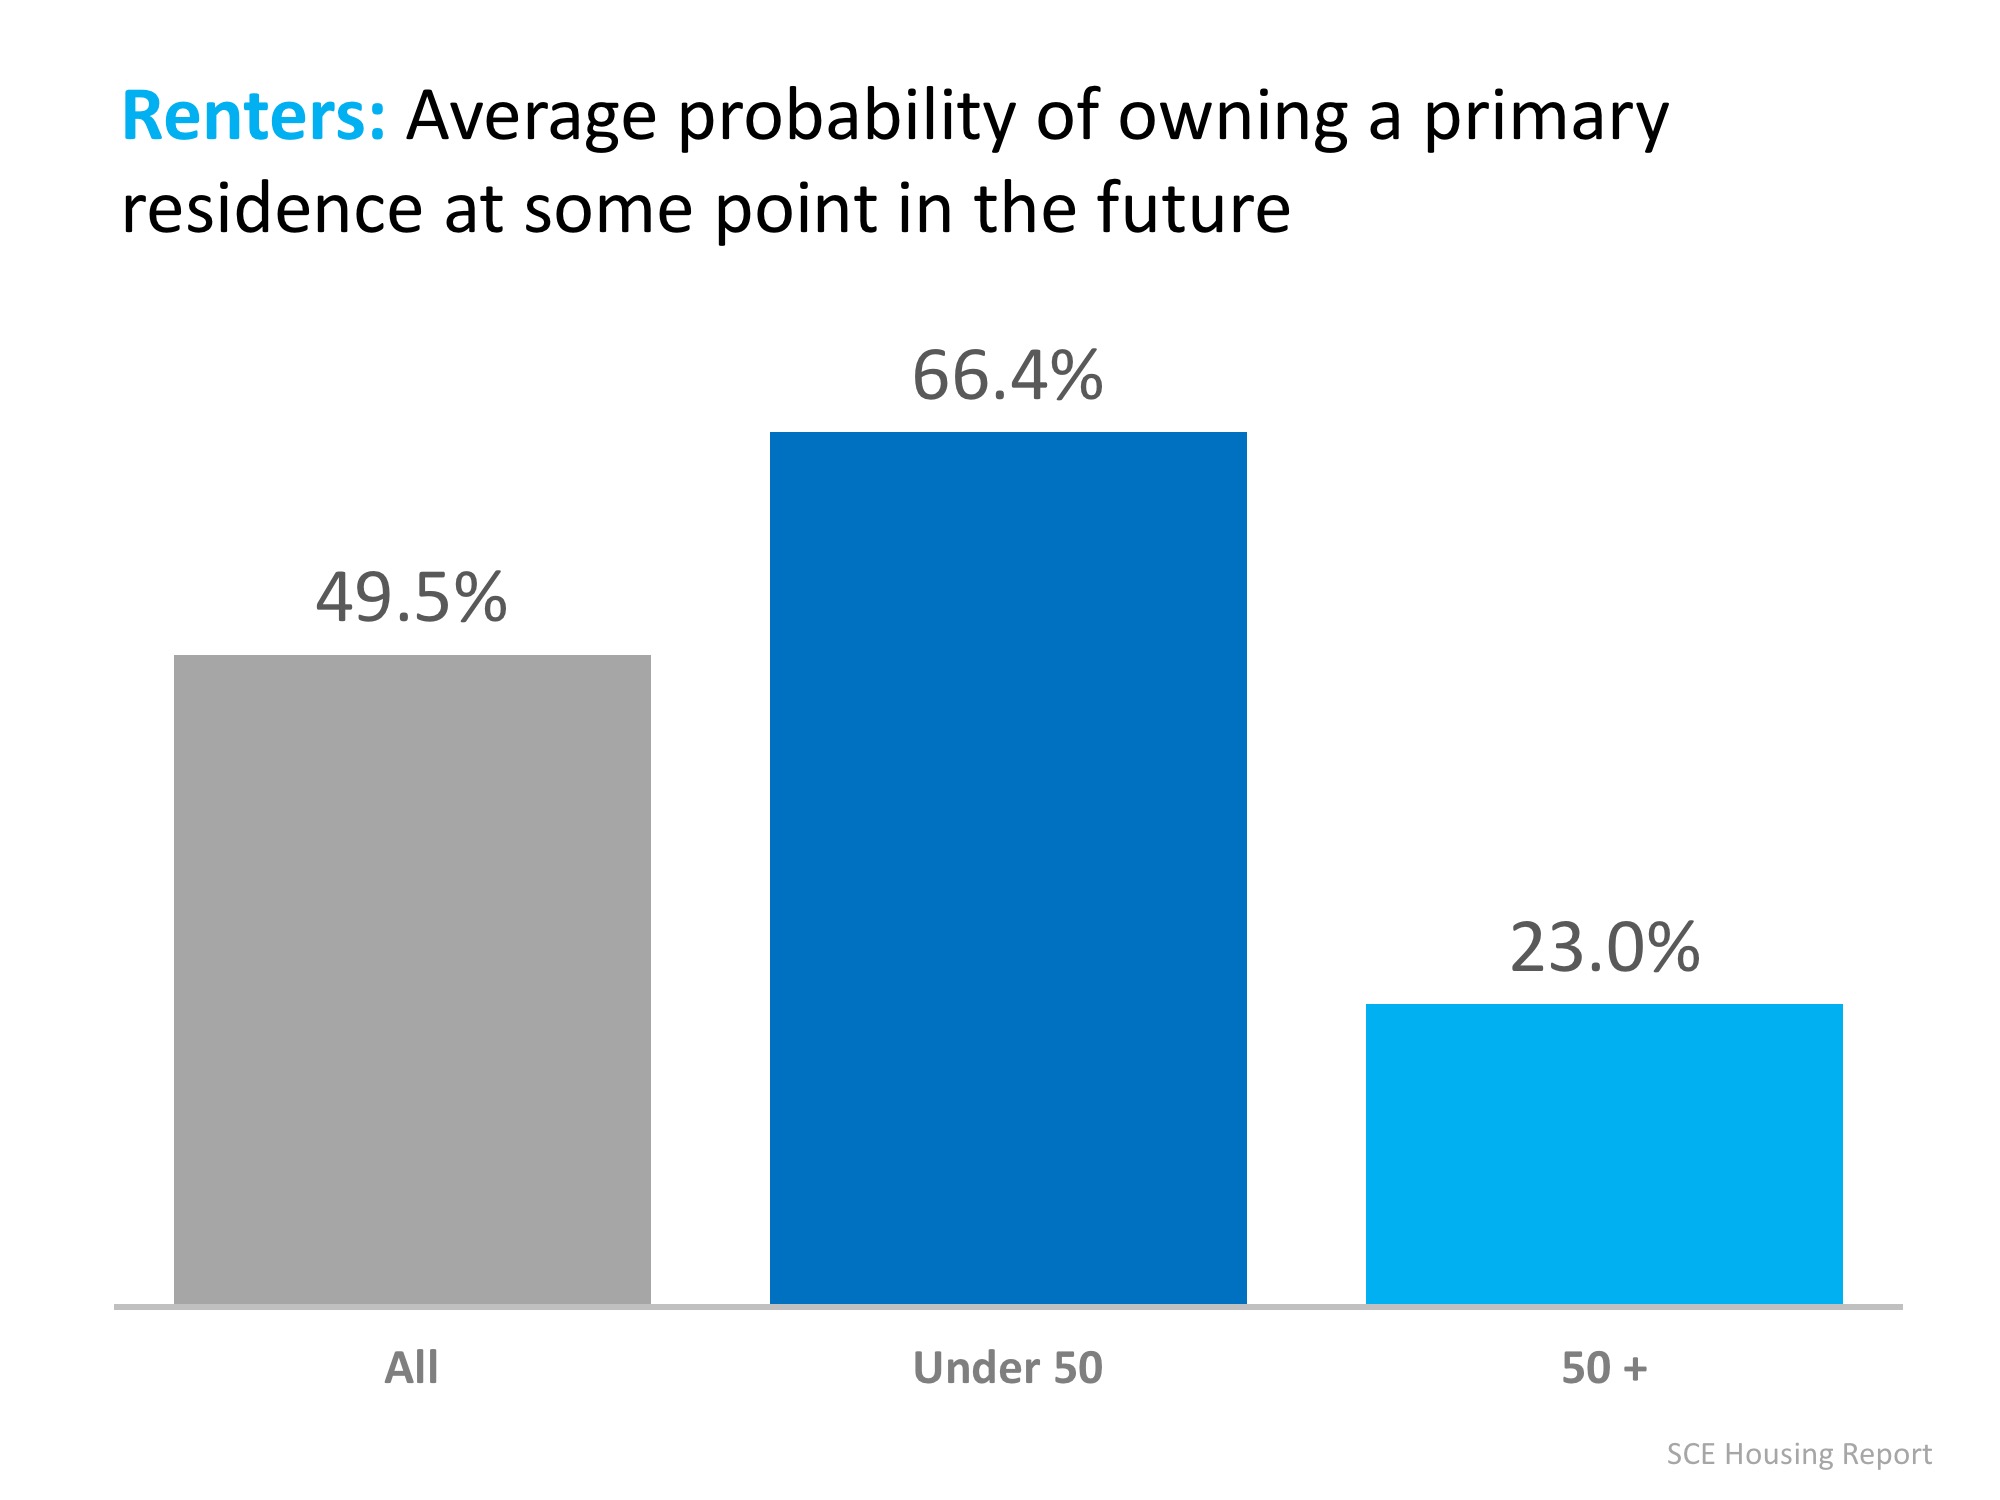
When renters were asked what the average probability of owning a primary residence at some point in their future was, 66.4% of those under 50 believed that they would eventually own their home, while only 23% of those over 50 did.
Bottom Line
Many had wondered if young Americans had lost their desire to own a home, but for those renting now, that dream is still alive.
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 & 2017 Recognition of Excellence Award Winner SDAR
One of the many questions asked in the housing section of the survey was:
Assuming you had the financial resources to do so, would you like to OWN instead of RENT your primary residence?
Over three-quarters of respondents under the age of 50 said that they would prefer to own their home, rather than rent. While only 52.6% of those over 50 would prefer to own. The full breakdown can be found in the chart below.
When renters were asked what the average probability of owning a primary residence at some point in their future was, 66.4% of those under 50 believed that they would eventually own their home, while only 23% of those over 50 did.
Bottom Line
Many had wondered if young Americans had lost their desire to own a home, but for those renting now, that dream is still alive.
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 & 2017 Recognition of Excellence Award Winner SDAR
Saturday, January 6, 2018
Should Boomers Buy or Rent after Selling?
In a recent CNBC article, it was reported that many baby boomers are selling their current homes and moving into rentals, rather than purchasing another home.
“Between 2009 and 2015, the number of renters aged 55 or above rose 28 percent, while those aged 34 or younger only increased 3 percent...
Meanwhile, more than 5 million baby boomers across the nation are expected to rent their next home by 2020, according to a 2016 analysis from Freddie Mac.”
This makes sense in the short term for many reasons. If you are moving to a different part of town or a new region of the country, you may decide to rent until you pick the perfect home in an area you love. However, is renting a good long-term strategy?
A mortgage payment remains fixed. Rents, however…
The Census Bureau recently released their 2017 third quarter median rent numbers. Here is a graph showing rent increases from 1988 until today:
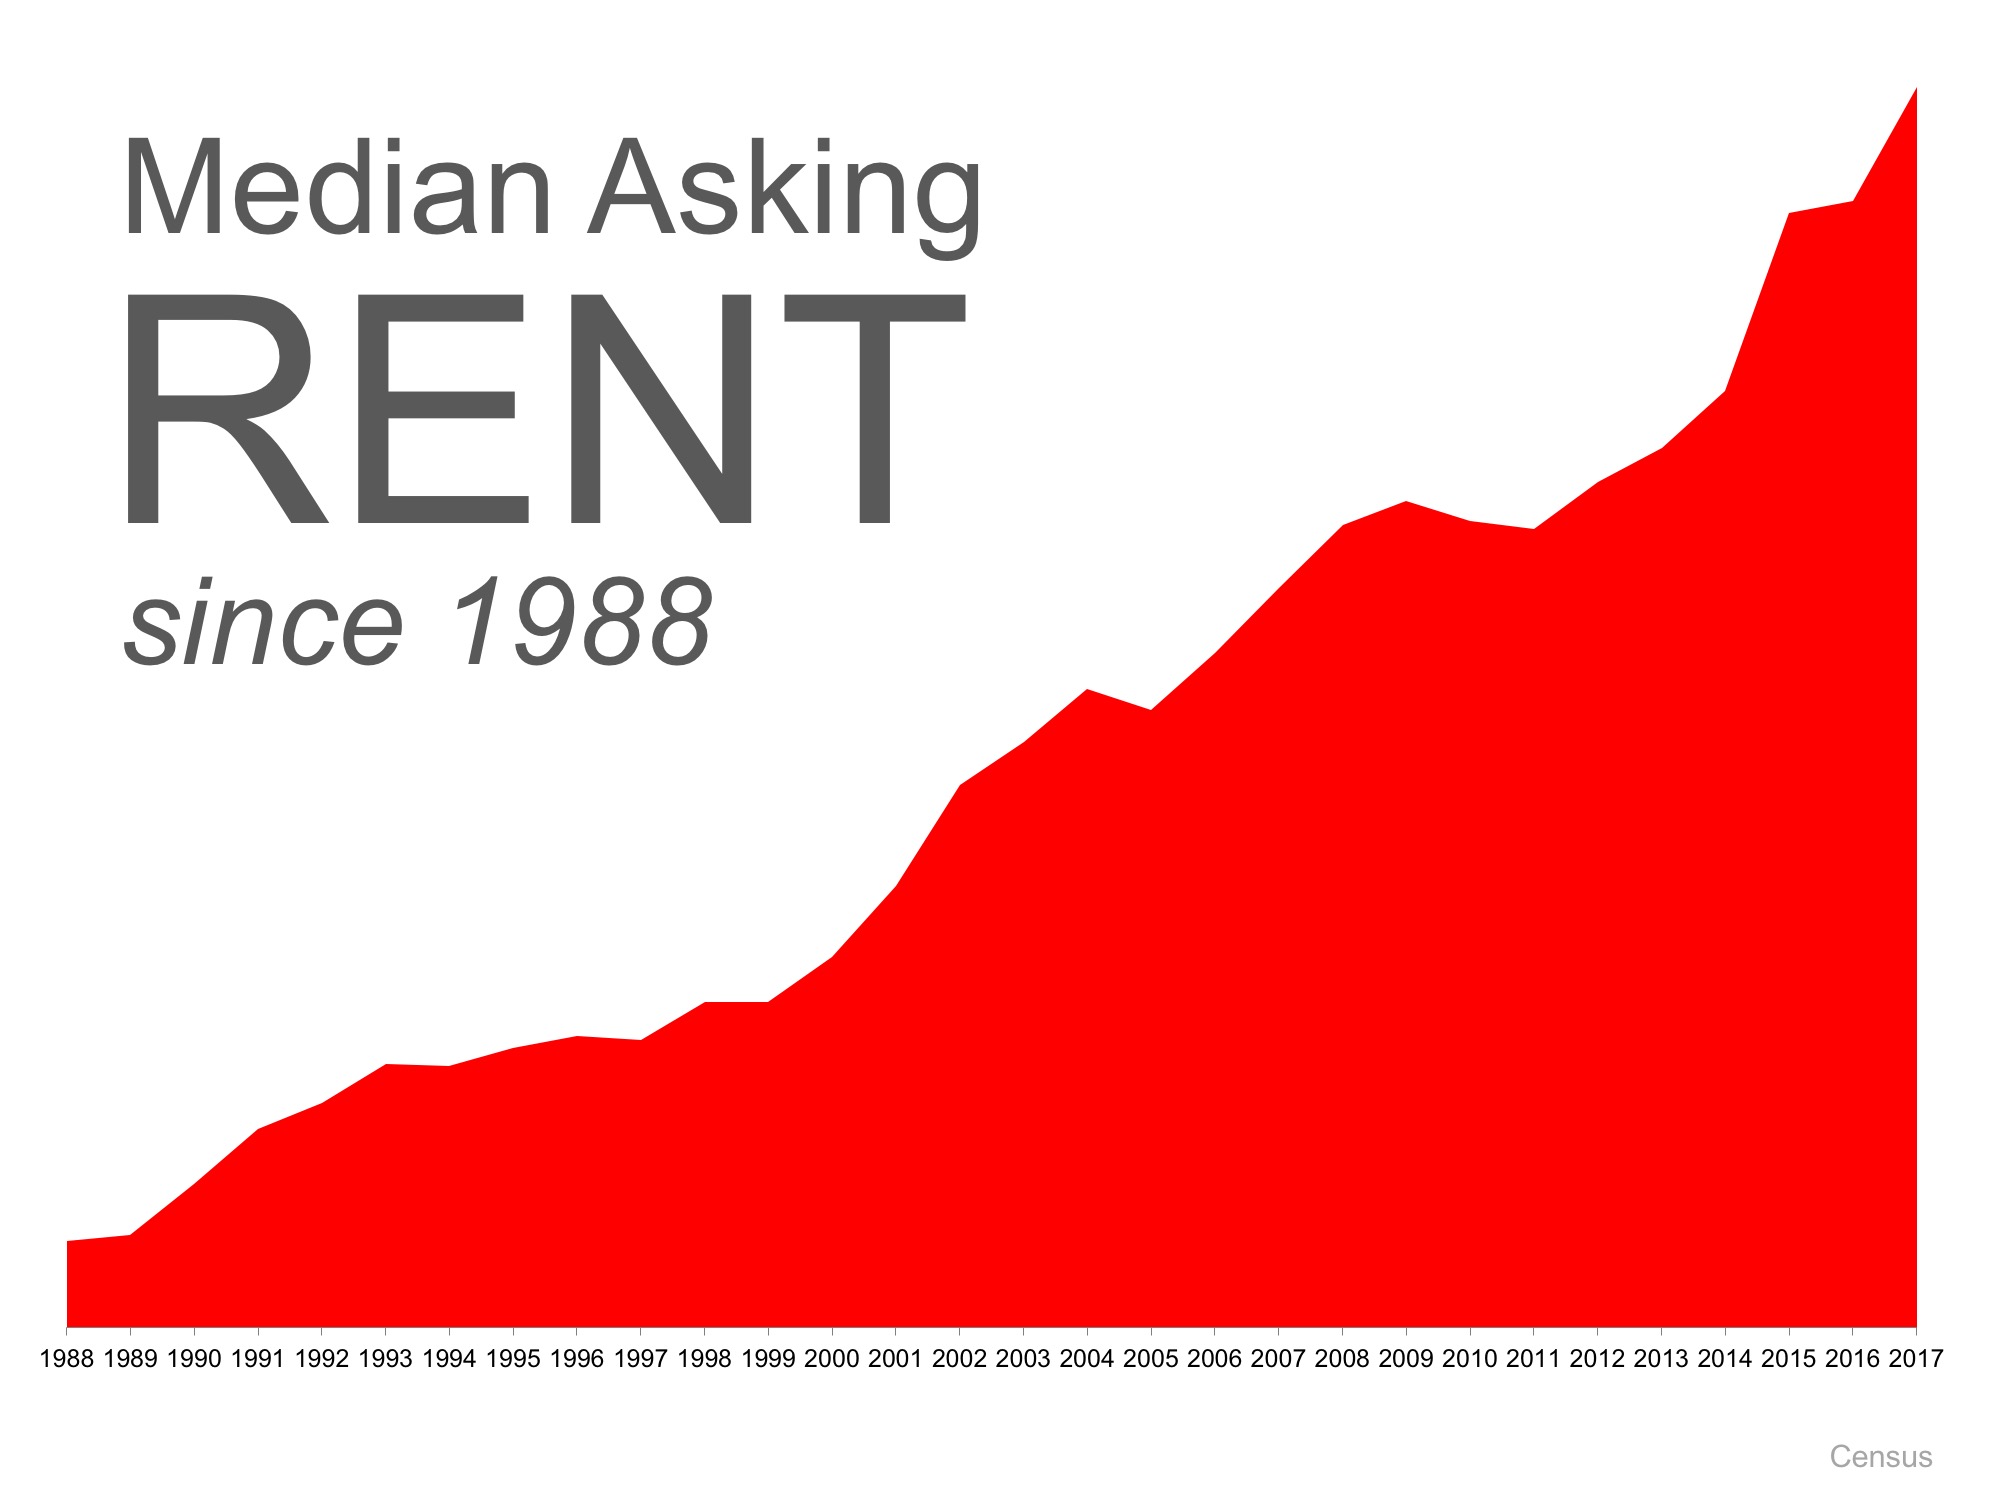
As you can see, rents have steadily increased and are showing no signs of slowing down. If you are faced with making the decision of whether you should rent or buy your next home, you should take this into consideration.
Bottom Line
One way to protect yourself from rising rents is to lock in your housing expense by buying a home instead of renting. Let’s get together so we can help you decide what the best step is for you and your family!
Looking to Buy, Sell, or Invest? Contact:
David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!
Saturday, June 27, 2015
Guess Where Residential Rents are Heading?
Each month, many people are faced with the
decision of renewing their rental lease for another year or purchasing their
first home. One of the questions that must be answered before they make a
decision is – “Where
are rents headed?” The Wall
Street Journal recently wrote an article on this issue. Their conclusion:
 “Apartment rental increases slowed in the
first quarter from a year earlier, but the move is more likely a temporary
blip than the beginning of a long-term respite for renters.”
The article goes on to quote Ryan Severino,
a senior economist at Reis:
“I wish I had a better story to tell renters
these days, but I think they’re in for some rent increases for the
foreseeable future.”
Probably the most interesting part of the
article came in the Comment Section where a proud landlord proclaimed:
“As a landlord I can tell you I don't pay
property tax. I don't pay for repairs. The tenant pays. I get my money off
the top.”
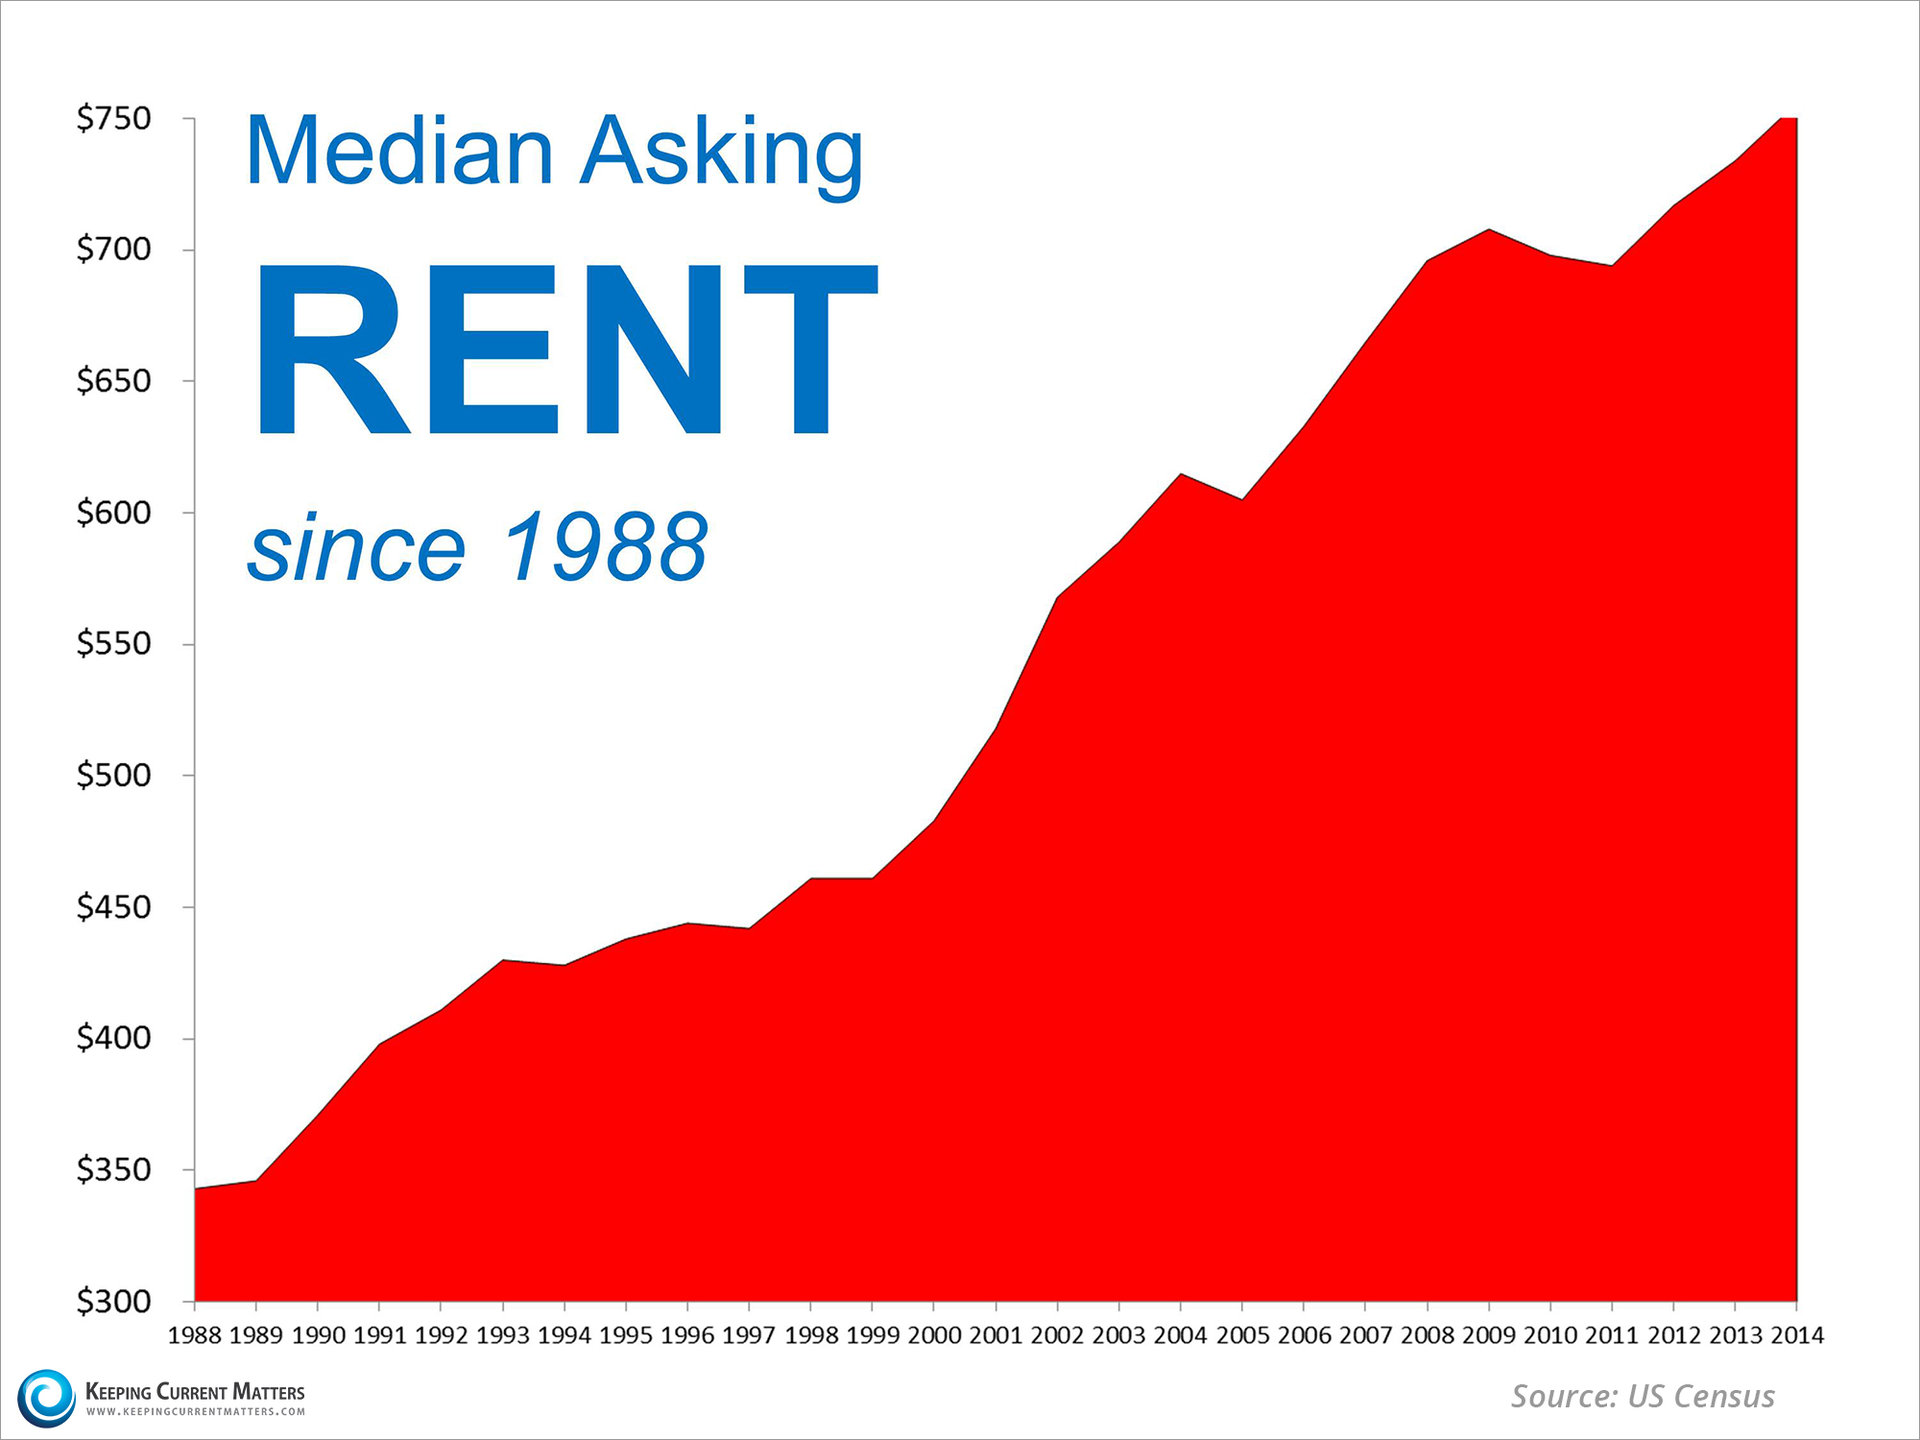
Here is a chart showing rent increases over
the last 25+ years:
 David Demangos 858.232.8410 Locally Known, Globally Connected Luxury Home Marketing Specialist Global Property Specialist David@AwesomeSanDiegoRealEstate.com www.AwesomeSanDiegoRealEstate.com Our Team Goes to Extremes to Fulfill Your Real Estate Dreams! |
Subscribe to:
Posts (Atom)