Showing posts with label buying a home in san diego. Show all posts

Wednesday, December 24, 2025

Moving to San Diego in 2026: Everything You Need to Know

San Diego has always been a coveted destination, and 2026 is no exception. Whether you're drawn by the beautiful beaches, the vibrant culture, or the booming job market, here’s a comprehensive guide to help you settle in.

1. Cost of Living
San Diego is known for its relatively high cost of living. Housing, in particular, tends to be the largest expense. While prices can vary depending on the neighborhood, you can expect higher-than-average rent and home prices compared to other U.S. cities.

2. Housing Market
The San Diego real estate market remains competitive. In 2026, you’ll find a mix of modern condos, charming bungalows, and spacious family homes. It’s essential to work with a local realtor to navigate the market effectively and find a property that fits your budget and lifestyle.

3. Job Market
San Diego’s economy is diverse, with strong sectors in biotechnology, telecommunications, defense, and tourism. The city also has a growing startup scene, making it an attractive destination for young professionals and entrepreneurs.

4. Lifestyle and Culture
From its world-famous beaches like La Jolla and Pacific Beach to its thriving arts scene, San Diego offers a laid-back yet vibrant lifestyle. There are plenty of outdoor activities, including hiking, surfing, and biking, as well as a rich culinary scene featuring fresh seafood and innovative cuisine.

5. Transportation
San Diego boasts a well-connected public transit system, including trolleys and buses, but many residents prefer driving. With ongoing infrastructure improvements, commuting is becoming more convenient.

6. Education and Schools
For families, San Diego offers a range of highly rated public and private schools, as well as prestigious universities such as UC San Diego. Education options are plentiful and cater to a diverse population.

7. Weather
One of San Diego’s biggest draws is its mild, Mediterranean climate. Expect plenty of sunshine and comfortable temperatures year-round, making it perfect for outdoor enthusiasts.

Moving to San Diego in 2026 promises a blend of opportunities and a high quality of life. With careful planning and a bit of local insight, you’ll find yourself right at home in this dynamic coastal city.

Ready to Make the Move?
If you’re considering relocating to San Diego or need assistance with buying or selling property, feel free to reach out to me:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams

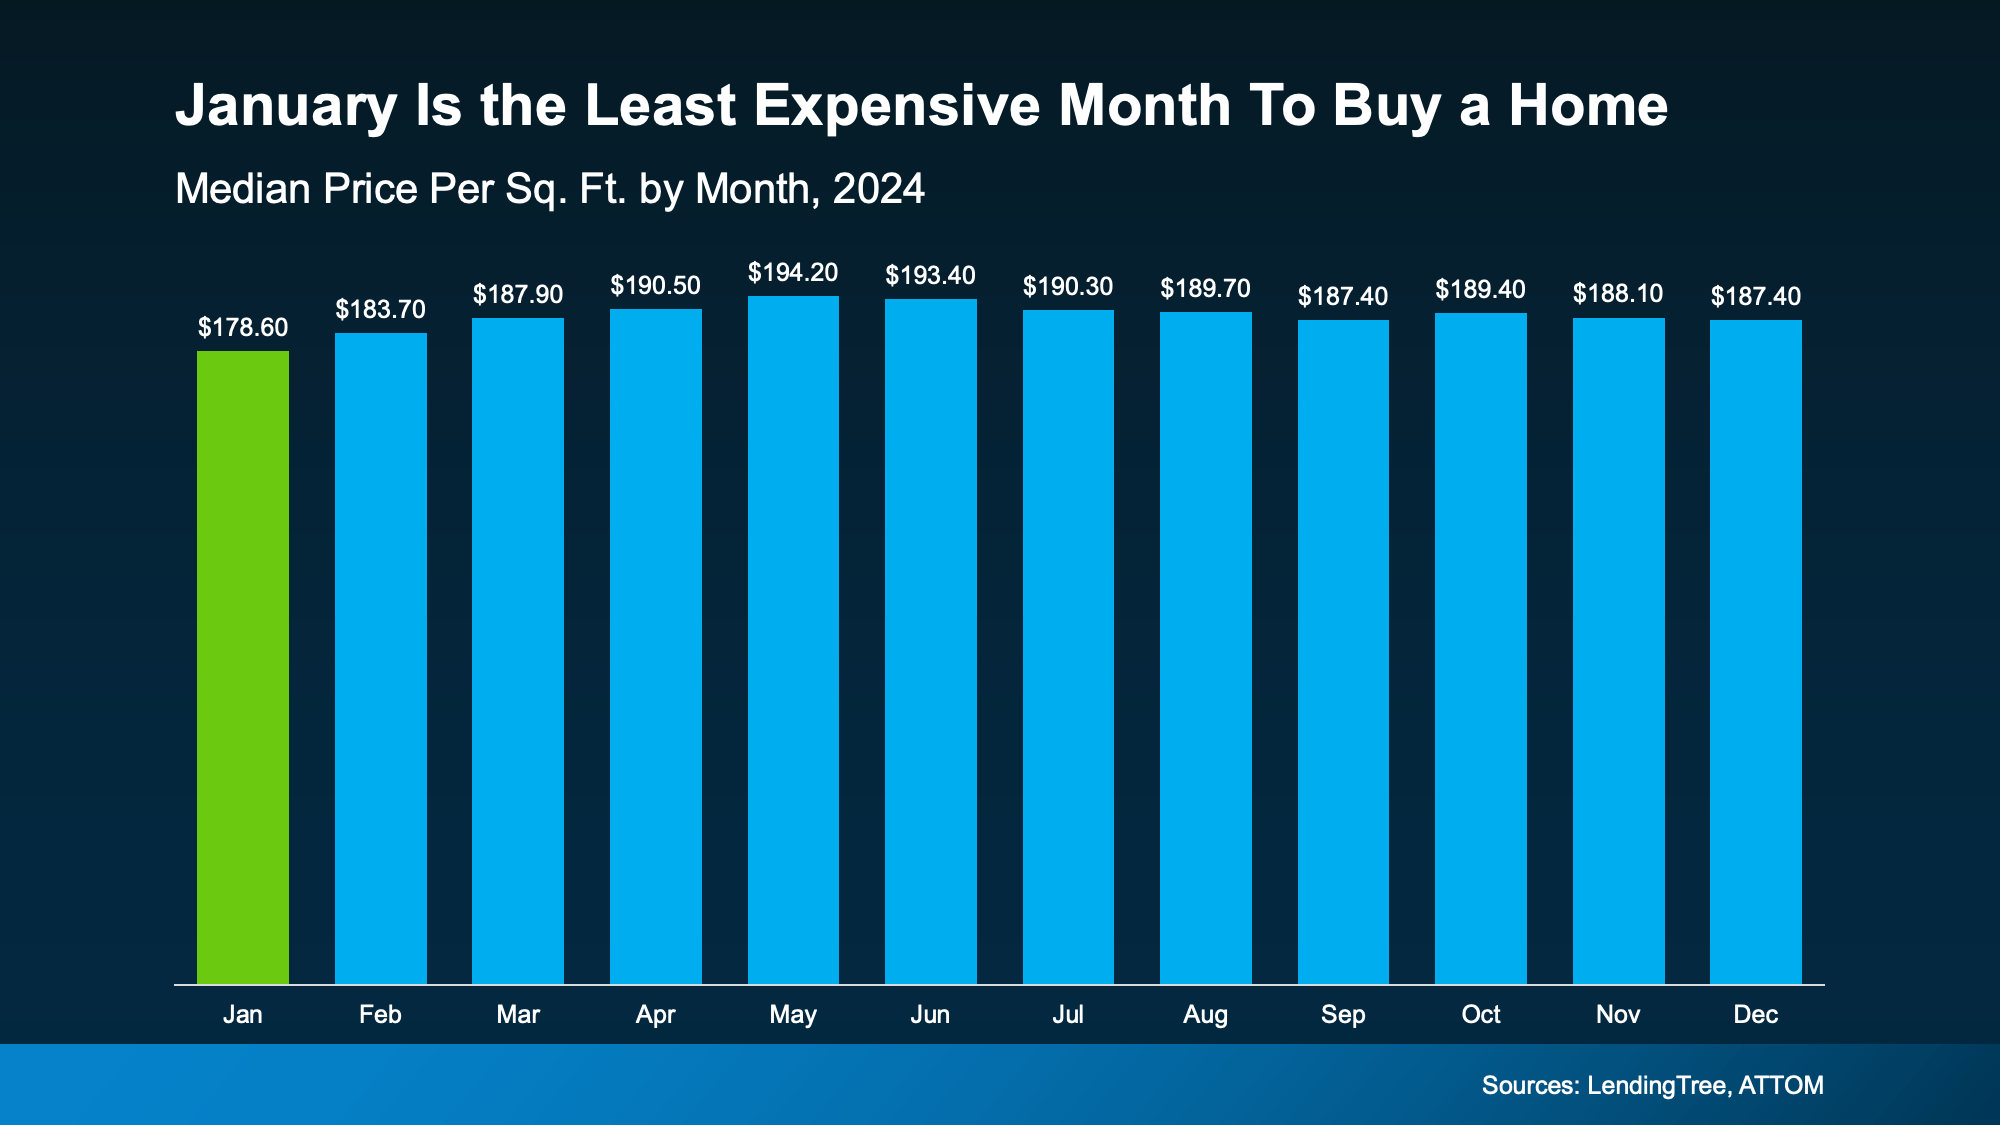
Tuesday, December 23, 2025

Is January the Best Time to Buy a Home?

You may not want to put your home-buying plans on hold this winter. While many people assume spring is the ideal time to buy a house, new data shows January is the best time of year for budget-conscious buyers. 

It's surprising, right? Here’s why January deserves a serious look

1. Prices Tend To Be Lower This Time of Year

Lending Tree says January is the least expensive month to buy a home. And there’s something to that. January has historically offered one of the lowest price-per-square-foot points of the entire year. But the spring? That’s when demand (and prices) usually peak. And that’s not speculation – it's a well-known trend based on years of market data.

a graph of a number of blue bars
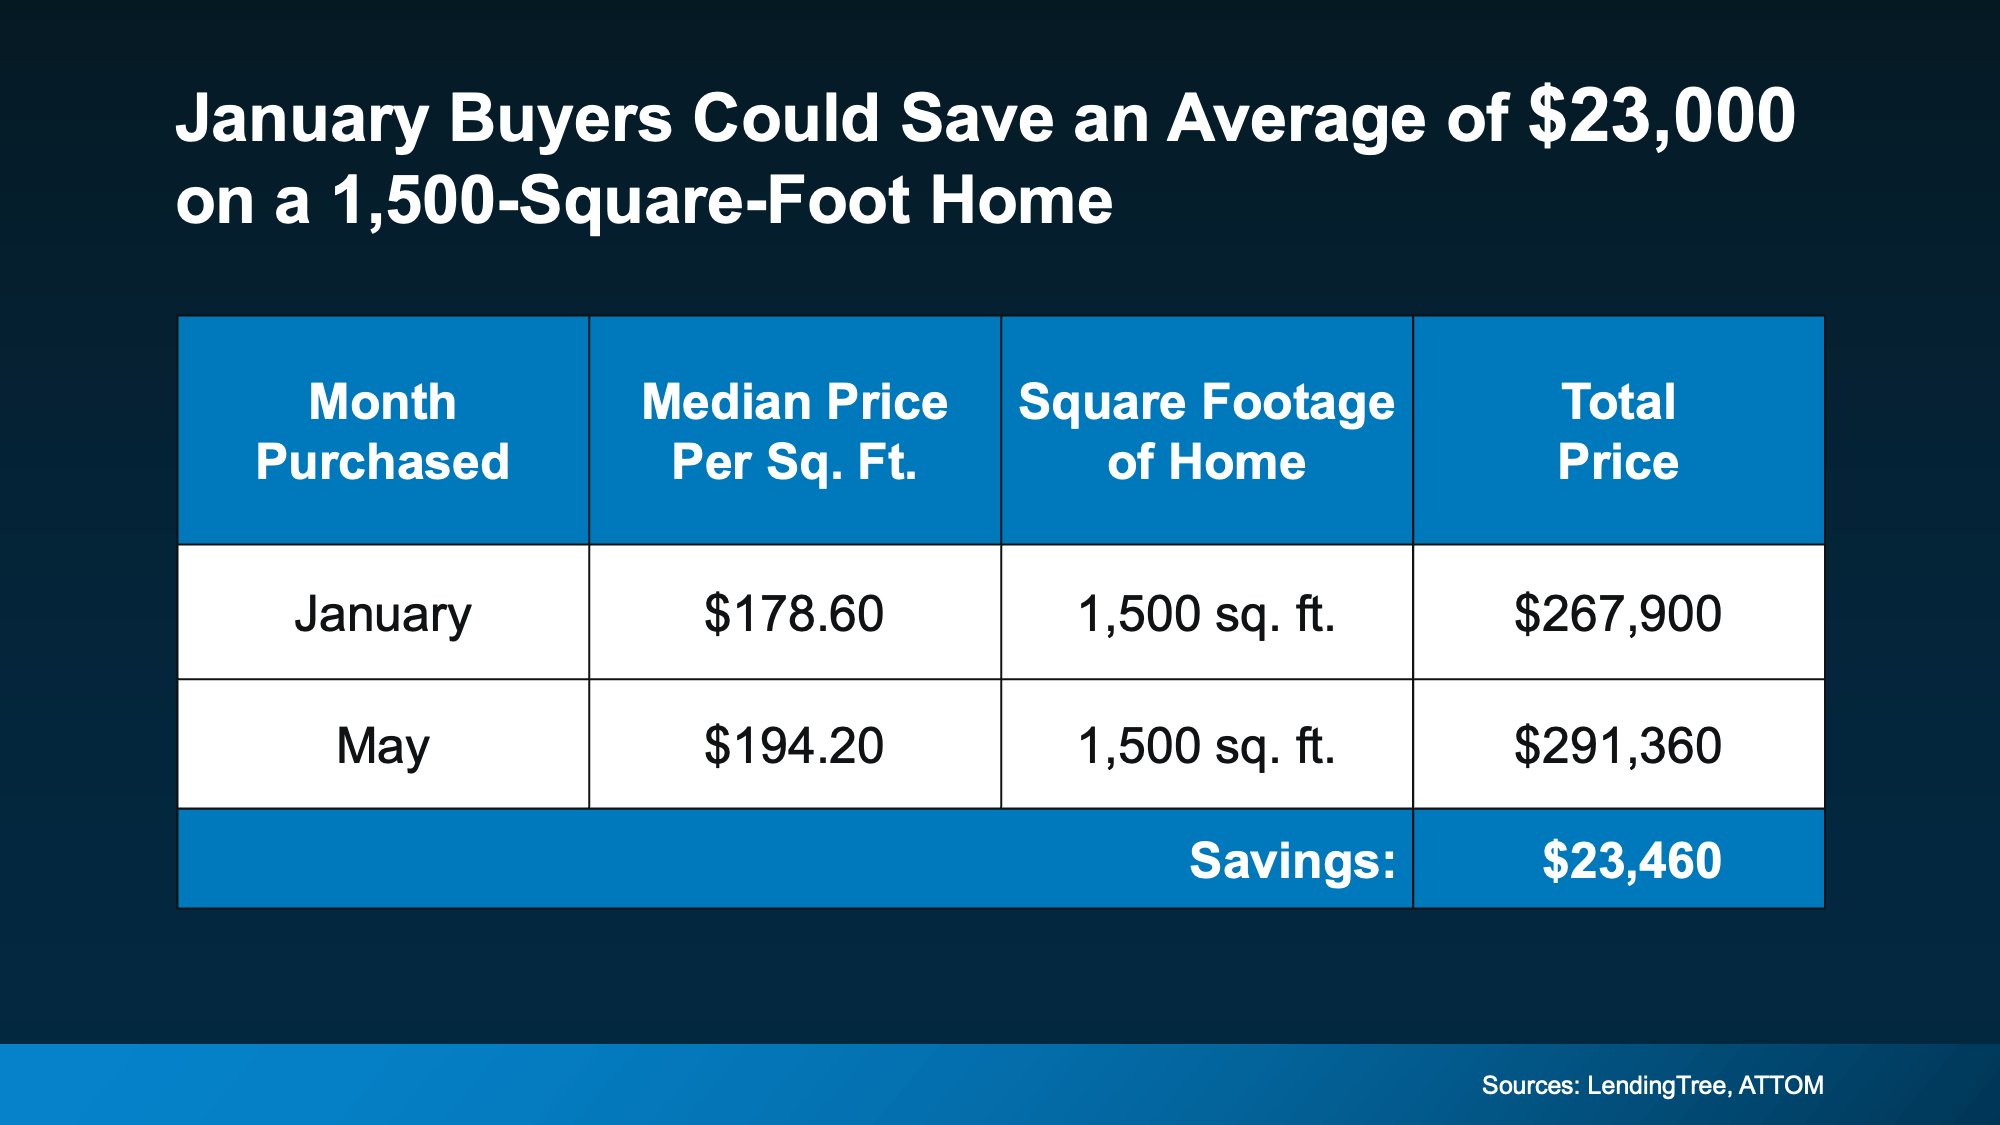
So, how much less are we talking? Here’s a look at the numbers. According to the last full year of data, for the typical 1,500 square foot house, buyers who closed on their home in January paid around $23,000 less compared to those who bought in May. And that general trend typically holds true each year (see chart below):

a blue and white table with white text
Now, your number is going to depend on the price, size, and type of the home you’re buying. But the trend is clear. For today’s buyers, it's meaningful savings, especially when affordability is still tight for so many households.

2. Fewer Buyers and More Motivated Sellers 

And why do buyers typically save in the winter? It’s simple. Winter is one of the slowest times in the housing market each year. Both buyers and sellers tend to pull back, thinking it’s better to wait until spring. And that means:

  • You face less competition
  • You’re less likely to get into a multiple offer scenario
  • Sellers are more willing to negotiate (since there aren’t as many buyers)

With fewer buyers in the market, you can take your time browsing.

But winter doesn’t just thin out the pool of buyers, it also reveals which sellers truly need to sell. Because fewer people are house hunting during the colder months, sellers who really need to move tend to be more open to negotiating. As Realtor.com explains:

“Less competition means fewer bidding wars and more power to negotiate the extras that add up: closing cost credits, home warranties, even repair concessions. . . these concessions can end up knocking thousands of dollars off the price of a home.”

This can include everything from price cuts to covering closing costs, adjusting timelines, and more. It doesn’t mean you’ll automatically get discounts on every home. But it does mean you’re more likely to be taken seriously and given room to negotiate.

Should You Wait for Spring?

Here’s the real takeaway. When you remove the pressure and frenzy that comes with the busy spring season, it becomes much easier to get the home you want at a price that fits your budget.

But if you wait until spring, more buyers will be in the market. So, waiting could actually mean you spend more and you’d have to deal with more stress.

Now, only you can decide the right timing for your life, but don't assume you should wait for warmer weather before you move.

Buying in January gives you: less competition, potentially lower prices, and more motivated sellers. And those are three perks you’re not going to see if you wait until spring.

Bottom Line

If you’ve been thinking about taking the next step, this season might give you more opportunity than you think.

Curious what buying in January could look like for you? Let’s take a closer look at your numbers and the homes that are available in our area.

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams
Thursday, December 11, 2025

Why Buying a Home Still Pays Off in the Long Run

Renting can feel much less expensive and much simpler than buying a home, especially right now. No repairs, no property taxes, no worrying about mortgage rates – you just pay the bill and move on with your life.


But here’s the part people don’t talk about enough: renting doesn’t help you build your financial future. Meanwhile, homeowners grow their net worth just by owning a home.

So, if you’ve been wondering whether buying is still worth it, the long-term math is clearer than you might think.


Renting vs. Owning: How the Costs Really Compare


Let’s break down one of the key differences between renting and buying. When you rent, your payment goes to your landlord, and then it’s gone. When you own, part of your payment comes back to you in the form of equity (the wealth you build as the value of your home increases, and you pay down your home loan).


So, while renting may seem more affordable now, you have to remember it comes at a long-term cost: you’re not building your wealth. And it turns out, that’s a bigger miss than you may expect.


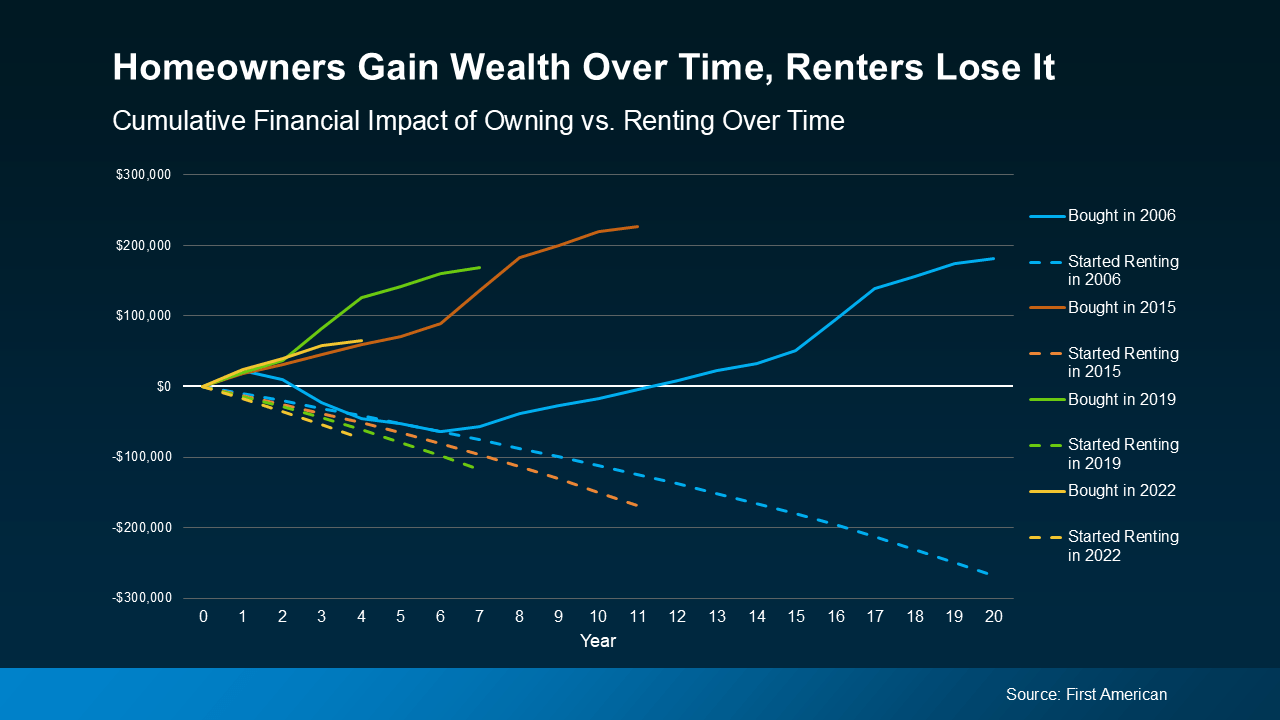
First American recently analyzed the long-term financial impact of renting versus owning a home. They compared mortgage payments, property tax, insurance, repairs, and maintenance against the equity gained through home price appreciation and paying down the mortgage. And they did that during several different time frames to see if it tells a consistent story:


  • 2006: the start of the housing bubble
  • 2015: 10 years ago
  • 2019: just before the pandemic (the last normal years in the market)
  • 2022: when mortgage rates jumped

In each time frame, two things were true: renters ended up losing money over time. And homeowners gained it.


Here’s some data so you can see this play out. Each color represents one of the key time frames. The solid lines show the buyer’s investment over time and how their net worth actually grew the longer they lived in their home. The dashed line represents the renter’s investment. In the end, they sank more and more cash into renting without gaining any financial benefit.


a graph of a graph showing the impact of owning vs renters loss

The takeaway is simple: time in a home builds wealth. Time renting doesn’t.

Basically, homeowners come out ahead. And the analysis shows that’s even after you factor in the other expenses that come with homeownership, like insurance, repairs, and property taxes. And that's the case for every time frame First American looked into.


On the flip side, renters spent money on their rent, but didn’t gain any long-term financial benefit. That’s true no matter what window of time you look at in the study.


Now, that doesn’t mean buying always beats renting in the short term. But the longer you own, the wider the wealth gap becomes.


Affordability Is Starting To Improve


You might still be thinking, “Okay, but buying feels out of reach for me right now.” Fair.

The past few years haven’t been easy for buyers. But things are starting to shift. Mortgage rates have come down this year, home prices are softening, and incomes have been rising. And according to Zillow, typical monthly payments have gotten a little easier compared to this time last year. Not by a lot, but enough to make a difference.


No, buying isn’t suddenly easy. But it is easier than it was just a few months ago. And in the long run, history shows it’s worth it. 

Bottom Line

Renting may feel less expensive today, but owning is what builds real wealth over time. And with affordability starting to improve, the path to homeownership may be opening up more than you think.


If you’re curious what buying could look like for you, let’s connect. We can figure out your next move, pressure-free.

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams
Saturday, January 4, 2025

Simple Steps To Help You Save for Your First Home

Turning a dream into reality starts with one thing: a plan. And if buying your first home is on your list of goals, now’s the perfect time to put a plan in motion to help you save.

And the best part? Reaching your savings goal doesn’t mean making huge sacrifices overnight – small, consistent steps can get you there over time. Here are a few strategies that can help speed up the process.

Step 1: Build a Budget That Works for You

Knowing where your money’s going is the first step to saving more of it. Take some time to track the money you’ve got coming in and going out. This helps you spot areas where you're spending more than you realize. It also helps to give yourself some guidelines on what you want to spend for groceries, gas, and more – try to stick to whatever caps you put on each spending category.

Step 2: Cut Down on Any Extras (It Adds Up)

Once you’ve got a clear budget, it’s time to tighten up. Look for areas where you can cut down your costs – like services you don’t really need – or ways you can reduce recurring expenses and put that money in your house fund instead. Every dollar you save now brings you closer to your future house. As Bankrate says:

“If you’re saving for a house, cutting back on your spending can help. Start with cutting unnecessary expenses, like subscription services, entertainment, delivery services or eating out. If possible, negotiate down recurring monthly or annual expenses, such as getting a better car insurance rate or reducing an internet bill . . . .”

Step 3: Automate Your Savings

Consistency is the real game-changer. If you have to transfer money manually, you may forget to do it. That’s why setting up automatic transfers to a dedicated savings account makes it easier to save regularly. Even apps that round up purchases to the nearest dollar and save the difference can help you build momentum without effort. As an article from Forbes explains:

“Automating your savings helps to keep your progress toward your goal consistent. Set up automatic transfers from your checking account to a dedicated savings account. This will help you prioritize saving and minimize the chances of spending your money on other things.”

Step Four: Put Any Extra Money To Work

Got a tax refund, work bonus, or a cash gift? Don’t fall into the temptation to spend it on something you don’t actually need. Use those unexpected boosts to make big strides toward your savings goal. Treating this extra cash as an opportunity, not just a nice surprise, will help you get there faster.

Bottom Line

Saving for your first house isn’t about perfection – it’s about progress. A solid plan, a little discipline, and a clear goal will take you further than you think. If you’re ready to make homeownership happen, let’s connect. We’ll map out the next steps together to get you closer to the keys to your first home.


David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams