Showing posts with label buying and selling a home in san diego. Show all posts

Thursday, December 16, 2021

Two Reasons Why Waiting To Buy a Home Will Cost You

If you’re a homeowner who’s decided your current house no longer fits your needs, or a renter with a strong desire to become a homeowner, you may be hoping that waiting until next year could mean better market conditions to purchase a home.

To determine whether you should buy now or wait another year, you can ask yourself two simple questions:
Where will home prices be a year from now?
Where will mortgage rates be a year from now?

Let’s shed some light on the answers to both of these questions.
Where Will Home Prices Be a Year from Now?

Three major housing industry entities are projecting ongoing home price appreciation in 2022. Here are their forecasts:

Fannie Mae: 7.4%
Freddie Mac: 7%
Mortgage Bankers Association: 5.1%

According to the National Association of Realtors (NAR), the median price of a home today is $353,900. Using an average of the three price projections above (6.5%), a home that sold for $353,900 today would be valued at $376,904 at the end of next year. As a prospective buyer, you would therefore pay an additional $23,004 by waiting.
Where Will Mortgage Rates Be a Year from Now?

Today, Freddie Mac announced their 30-year fixed mortgage rate was at 3.1%. However, most experts believe mortgage rates will rise as the economy recovers. Here are the forecasts for the fourth quarter of 2022 by the three major entities mentioned above:
Fannie Mae: 3.4%
Freddie Mac: 3.7%
Mortgage Bankers Association: 4%

That averages out to 3.7% if you include all three forecasts. Any increase in mortgage rates will increase your costs.
What Does It Mean for You if Home Values and Mortgage Rates Increase?

If both variables increase, you’ll pay a lot more in mortgage payments each month. Let’s assume you purchase a $353,900 home today with a 30-year fixed-rate loan at 3.1% (the current rate from Freddie Mac) after making a 10% down payment. According to mortgagecalculator.net, your monthly mortgage payment would be approximately $1,360 (this does not include insurance, taxes, and other fees because those vary by location).

That same home one year from now could cost $376,904, and the mortgage rate could be 3.7% (based on the industry forecasts mentioned above). Your monthly mortgage payment after putting down 10%, would be approximately $1,561.
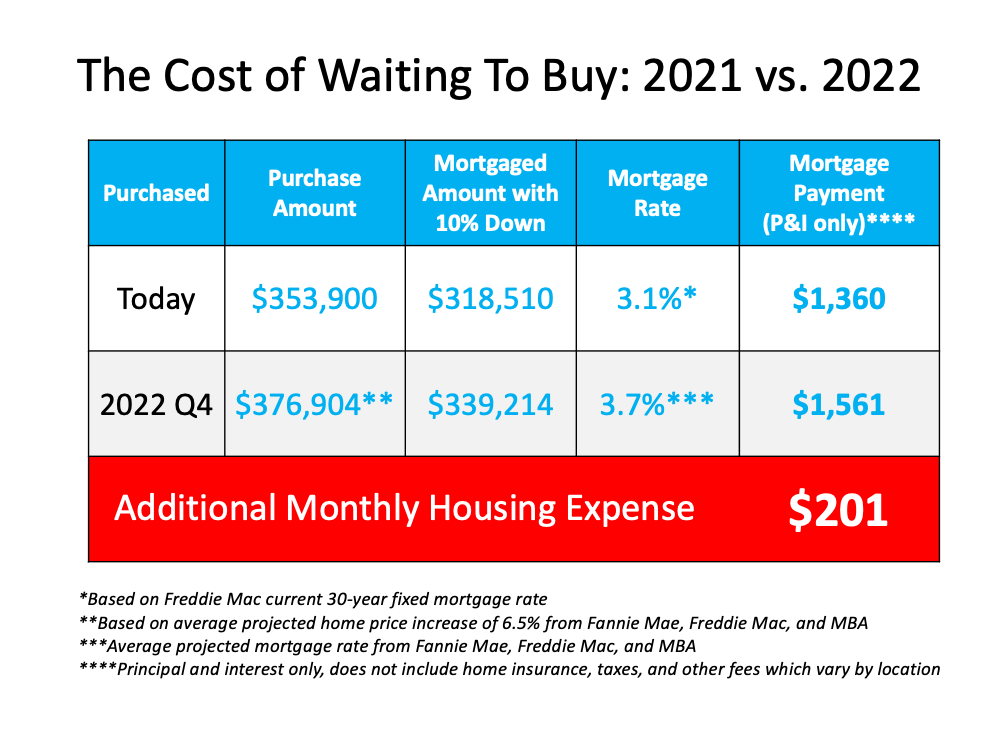

The difference in your monthly mortgage payment would be $201. That’s $2,412 more per year and $72,360 over the life of the loan.

Add to that the approximately $23,004 a house with a similar value would build in home equity this year due to home price appreciation, and the total net worth increase you could gain by buying this year is over $95,364 (the $72,360 mortgage savings plus the $23,004 potential gain in equity if you buy now).

Bottom Line

When asking if you should buy a home, you may think of the non-financial benefits of homeownership. When asking when to buy, the financial benefits make it clear that doing so now is much more advantageous than waiting until next year.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR

Tuesday, November 23, 2021

Sellers: You’ll Likely Get Multiple Strong Offers This Season

Are you thinking about selling your house right now, but you’re not sure you’ll have the time to do so as the holidays draw near? If so, consider this: even as the holiday season approaches, there are plenty of buyers out there, and they really want your house. Here’s why selling this winter is a win for you.

Today’s buyers are still dealing with a limited number of homes for sale. Thanks to continued low inventory, those buyers are competing with one another for their dream home. And when that happens, if your house is one of the few on the market, it will rise to the top of the pool – and it will be worth it.

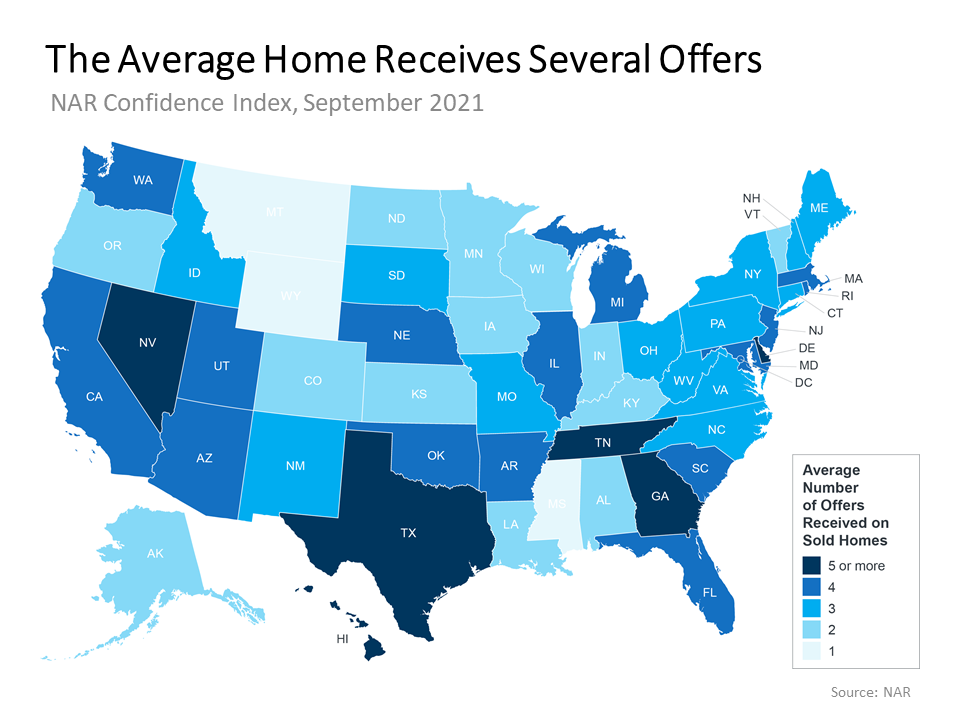
According to the latest data from the National Association of Realtors (NAR), the average seller received 3.7 offers on their house in September. For a view into what’s happening at the state level, take a look at the map below:


Nationwide, the average seller today is getting nearly four offers. That number is significant because it means you’ll likely have multiple offers to pick from if you sell your house this season. To put things into perspective, no matter where your state falls, remember that you really only need one good offer to close the deal.

Any offer you receive will likely be from a highly motivated buyer who’s doing everything they can to beat the competition. The stakes for buyers are high. They’ve been looking for a house and they want to lock in their dream home before prices and mortgage rates rise further next year. Chances are, they’ll get creative with the terms of their offer, which could include waiving contingencies and offering over the asking price – both of which are great news for you.

If you’re on the fence about when to sell, remember your house is a hot commodity this season. As other sellers take a break for the holidays with plans to re-list their homes in the new year, you can put your house in front of motivated buyers by making your move today. That means your house will be the center of attention, and likely the center of a bidding war too.

Bottom Line

Selling now gives you even more opportunity to win big as buyers compete for your house in today’s market.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR
Monday, November 23, 2020

Tips to Sell Your House Safely Right Now


Some Highlights:

Your agent now has over 6 months of experience selling houses during the pandemic and can make the process easier and safer for you today.
COVID-19 protocols and technology usage recommendations from the National Association of Realtors (NAR) are making it possible to sell houses right now, while agents continue to abide first and foremost by state and local regulations.

Let’s connect to discuss how to sell your house safely in today’s housing market.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR

Wednesday, November 4, 2020

How to Prepare for a Bidding War


Some Highlights:

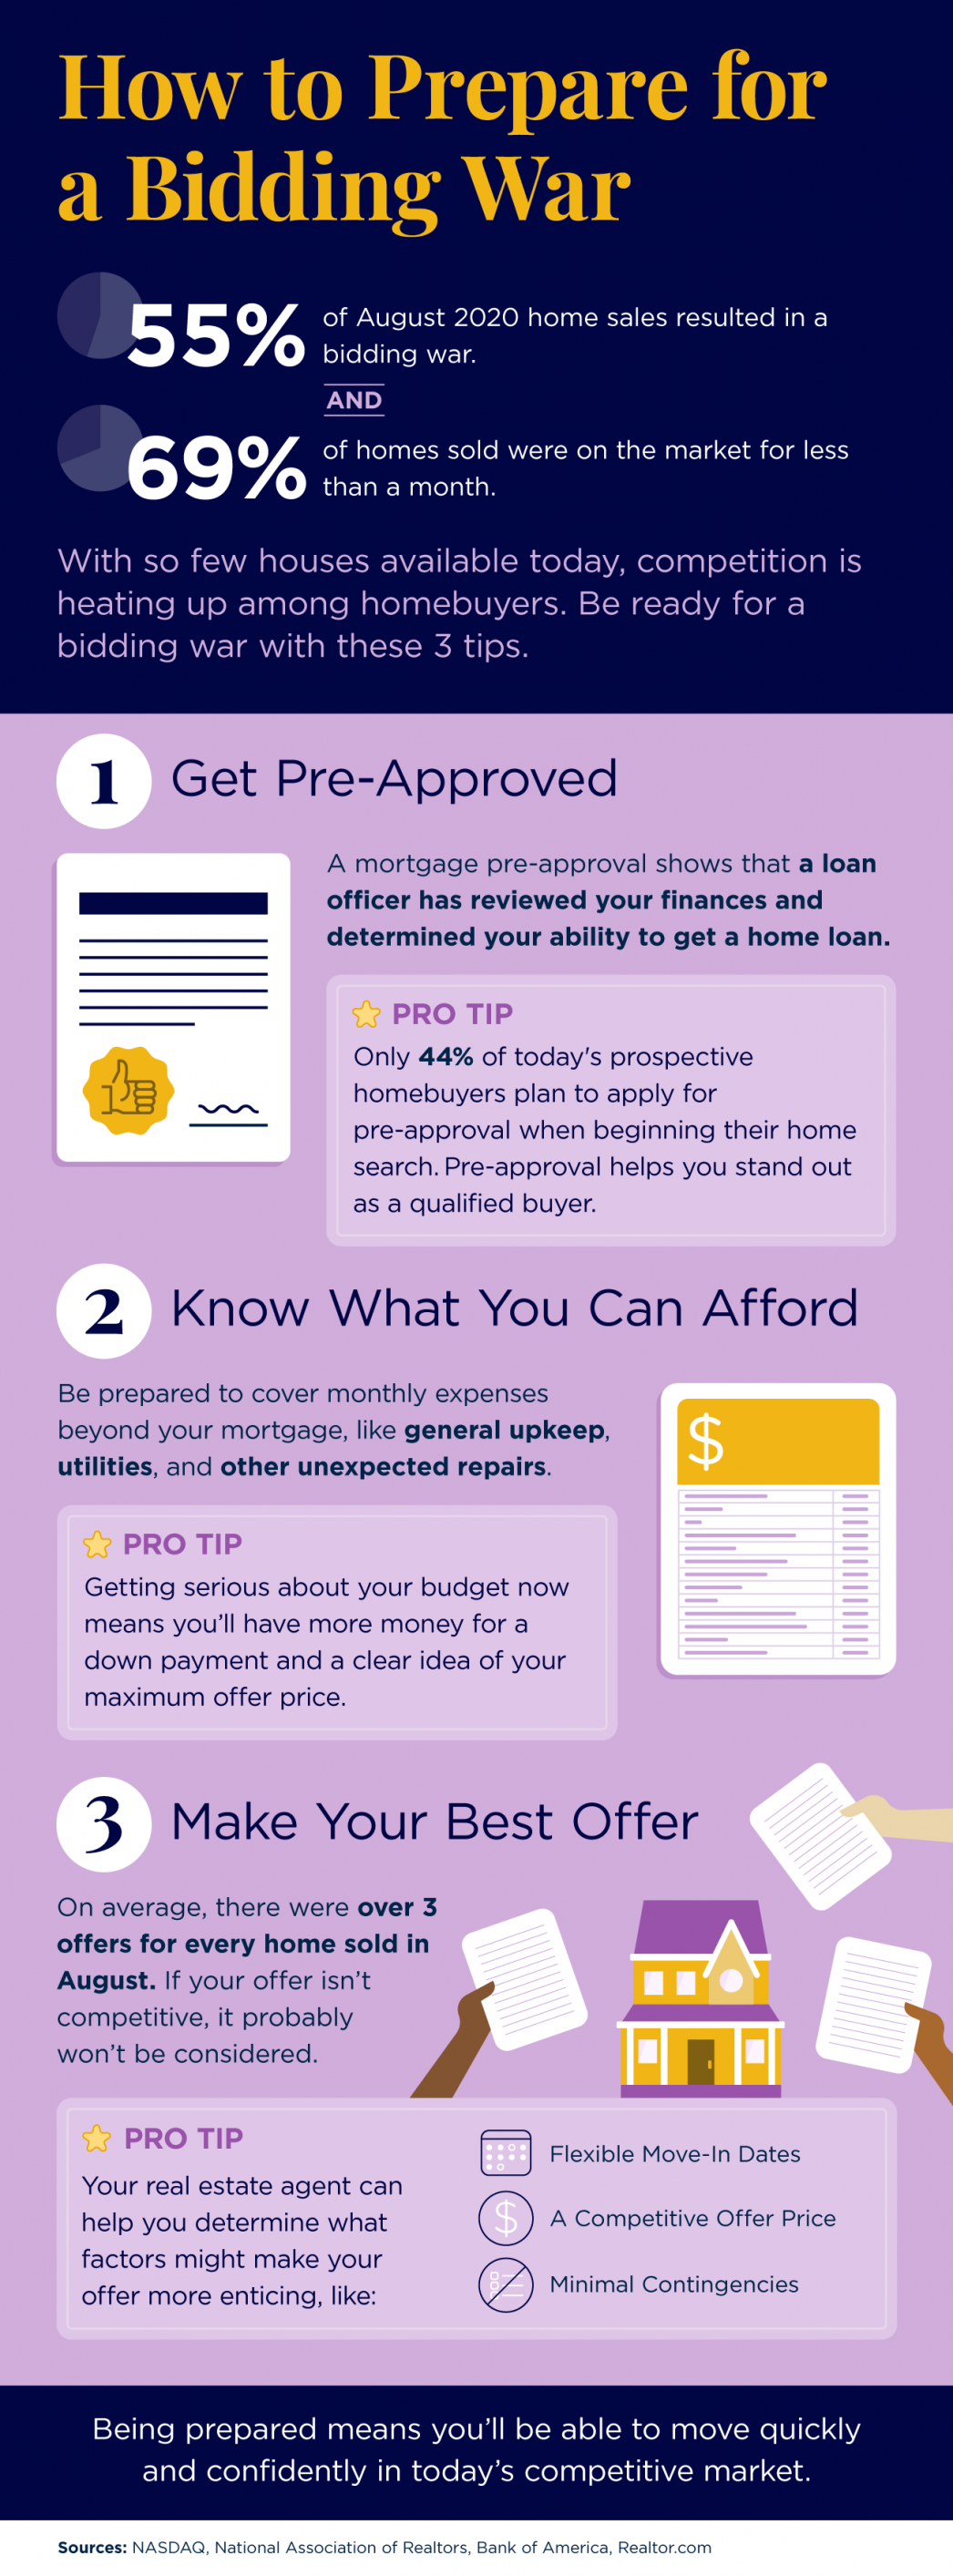
With so few houses available on the market today, being ready for a bidding war is essential for prospective homebuyers.
From pre-approval to making your best offer, here are three tips to make sure you can act quickly and confidently when you find the perfect home.
Let’s connect today to be sure you have the guidance you need as the competition for homes heats up this season.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR
Tuesday, October 27, 2020

The #1 Reason Not to Wait to List Your House for Sale

Many industries have been devastated by the economic shutdown caused by the COVID-19 virus. Real estate is not one of them.

Mark Fleming, Chief Economist for First American, just reported:

“Since hitting a low point during the initial stages of the pandemic, the only major industry to display immunity to the economic impacts of the coronavirus is the housing market. Housing has experienced a strong V-shaped recovery and is now exceeding pre-pandemic levels.”

Buyer demand is still strong heading into the fall. ShowingTime, which tracks the average number of buyer showings on residential properties, just announced that buyer showings are up 61.9% compared to the same time last year. They went on to say:

“Normally, real estate activity begins to slow down in the late summer, but this year it peaked in July, August and into September.”
There Is One Big Challenge

Purchaser demand is so high, the market is running out of available homes for sale. Just last week, realtor.com reported:

“Since the beginning of the COVID pandemic in March, nearly 400,000 fewer homes have been listed compared to last year, leaving a gaping hole in the U.S. housing inventory.”

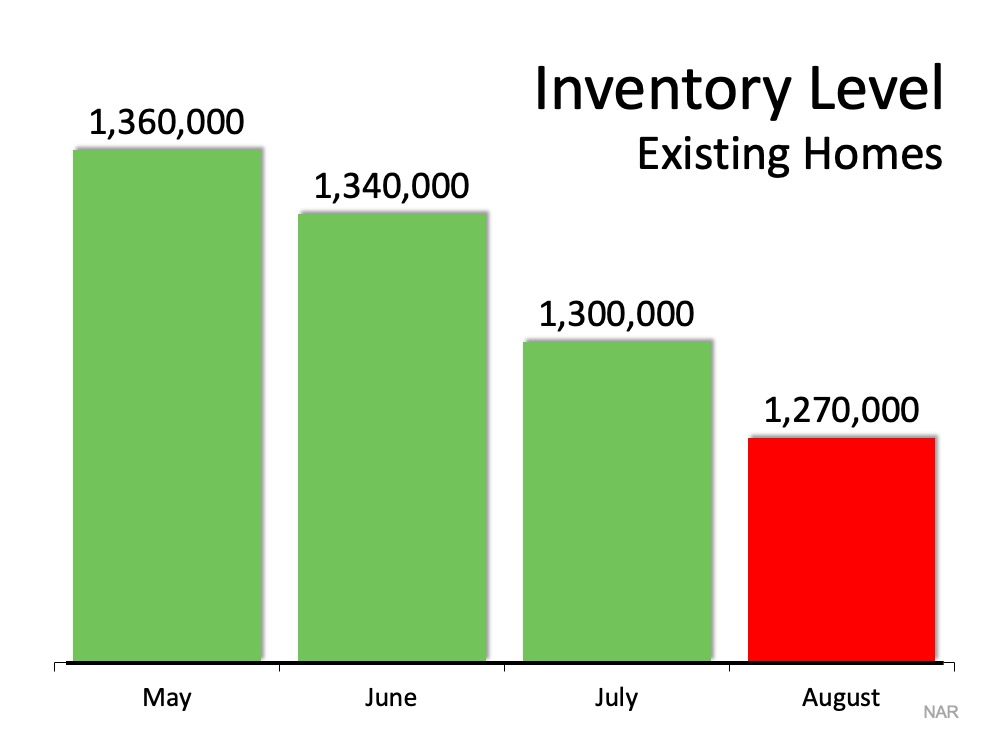
The National Association of Realtors (NAR) revealed that, while home sales are skyrocketing, the inventory of existing homes for sale is dropping dramatically. Below is a graph of existing inventory (September numbers are not yet available):


Homebuilders are increasing construction, but they cannot keep up with the high demand. Bill McBride, founder of the Calculated Risk blog, in discussing inventory of newly constructed houses, notes:

“The months of supply decreased to 3.3 months…This is the all-time record low months of supply.”
What does this mean for sellers?

Anyone thinking of putting their home on the market should not wait. A seller will always negotiate the best deal when demand is high and supply is limited. That’s exactly the situation in the real estate market today.

Next year, when the pandemic is hopefully behind us, there will be many more properties coming to the market. Don’t wait for that increase in competition in your neighborhood. Now is the time to sell.

Bottom Line

Let’s connect today to get your house on the market at this optimal time to sell.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Your Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR

Tuesday, August 18, 2020

Current Buyer & Seller Perks in the Housing Market


Today’s housing market is making a truly impressive turnaround, and it’s also setting up some outstanding opportunities for buyers and sellers. Whether you’re thinking of buying or selling a home this year, there are perks today that are rarely available, and definitely worth looking into.


Here are the top two.

The Biggest Perk for Buyers: Low Mortgage Rates

The most impressive buyer incentive today is the average mortgage interest rate. Just last week, mortgage rates hit an all-time low for the eighth time this year. The 30-year fixed-rate is now averaging 2.88%, the lowest rate in the survey’s history, which dates back to 1971 (See graph below):This is a huge advantage for buyers. To put it in perspective, it means that today you can get a lower rate than any of the past two generations of homebuyers in your family if you decide to purchase at this time.

In addition, the National Mortgage News notes how today’s buyers have increasing purchasing power due to these low mortgage rates:

“Purchasing power rose 10% year-over-year…With interest rates hitting record lows, buyers were able to afford $32,000 “more house” as of July 23 than they could the year before with the same monthly payment.”

This is a great perk for buyers who are hoping to potentially get more for their money in a home, something many are considering today as they re-evaluate the amount of space they ideally need for their families. It is an opportunity not seen in 50 years, and one not to be missed if the time is right for you to buy a home.
The Biggest Perk for Sellers: Low Inventory

Today, there are simply not enough houses on the market for the number of buyers looking to purchase them. According to the National Association of Realtors (NAR):

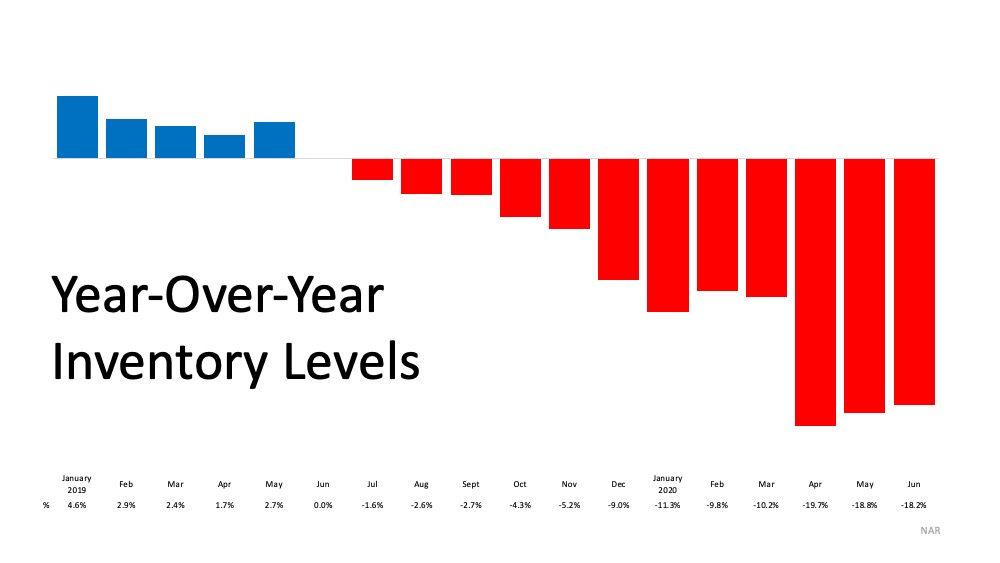
“Total housing inventory at the end of June totaled 1.57 million units, up 1.3% from May, but still down 18.2% from one year ago (1.92 million).”

The red bars in the graph below indicate that the inventory of homes coming into the market continues to decline. It was low as we entered the pandemic and has reduced even further this year. Houses today are selling faster than they’re being listed, and that’s creating an even greater supply shortage (See graph below):

The lack of inventory has been a challenging situation for a while now, and with low mortgage rates fueling buyer demand, inventory is even harder for buyers to find today. Buyers are eager to purchase, and because of the shortage of homes available, they’re encountering more bidding wars. This is one of the factors keeping home prices strong, an advantage for sellers. Lawrence Yun, Chief Economist for NAR notes that this trend may continue, too:

“Home prices rose during the lockdown and could rise even further due to heavy buyer competition and a significant shortage of supply.”

With low inventory and high buyer demand, homeowners can potentially earn an increasing profit on their houses and sell them quickly in this sizzling summer market.

Bottom Line

Whether you’re thinking about buying or selling at home, there are some key perks available right now. Let’s connect today to discuss how they may play to your advantage in our local market.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - eXp Realty
Cell: 858.232.8410 | Realtor® DRE# 01905183
www.AwesomeSanDiegoRealEstate.com
We Go to Extremes to Fulfill Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016, 2017, 2018,& 2019 Recognition of Excellence Award Winner SDAR
Thursday, October 11, 2018

2 Factors to Watch in Today’s Real Estate Market Whether Buying or Selling

When it comes to buying or selling a home there are many factors you should consider. Where you want to live, why you want to buy or sell, and who will help you along your journey are just some of those factors. When it comes to today’s real estate market, though, the top two factors to consider are what’s happening with interest rates & inventory.

Interest Rates

Mortgage interest rates have been on the rise and are now over three-quarters of a percentage point higher than they were at the beginning of the year. According to Freddie Mac’s latest Primary Mortgage Market Survey, rates climbed to 4.72% for a 30-year fixed rate mortgage last week.

The interest rate you secure when buying a home not only greatly impacts your monthly housing costs, but also impacts your purchasing power.

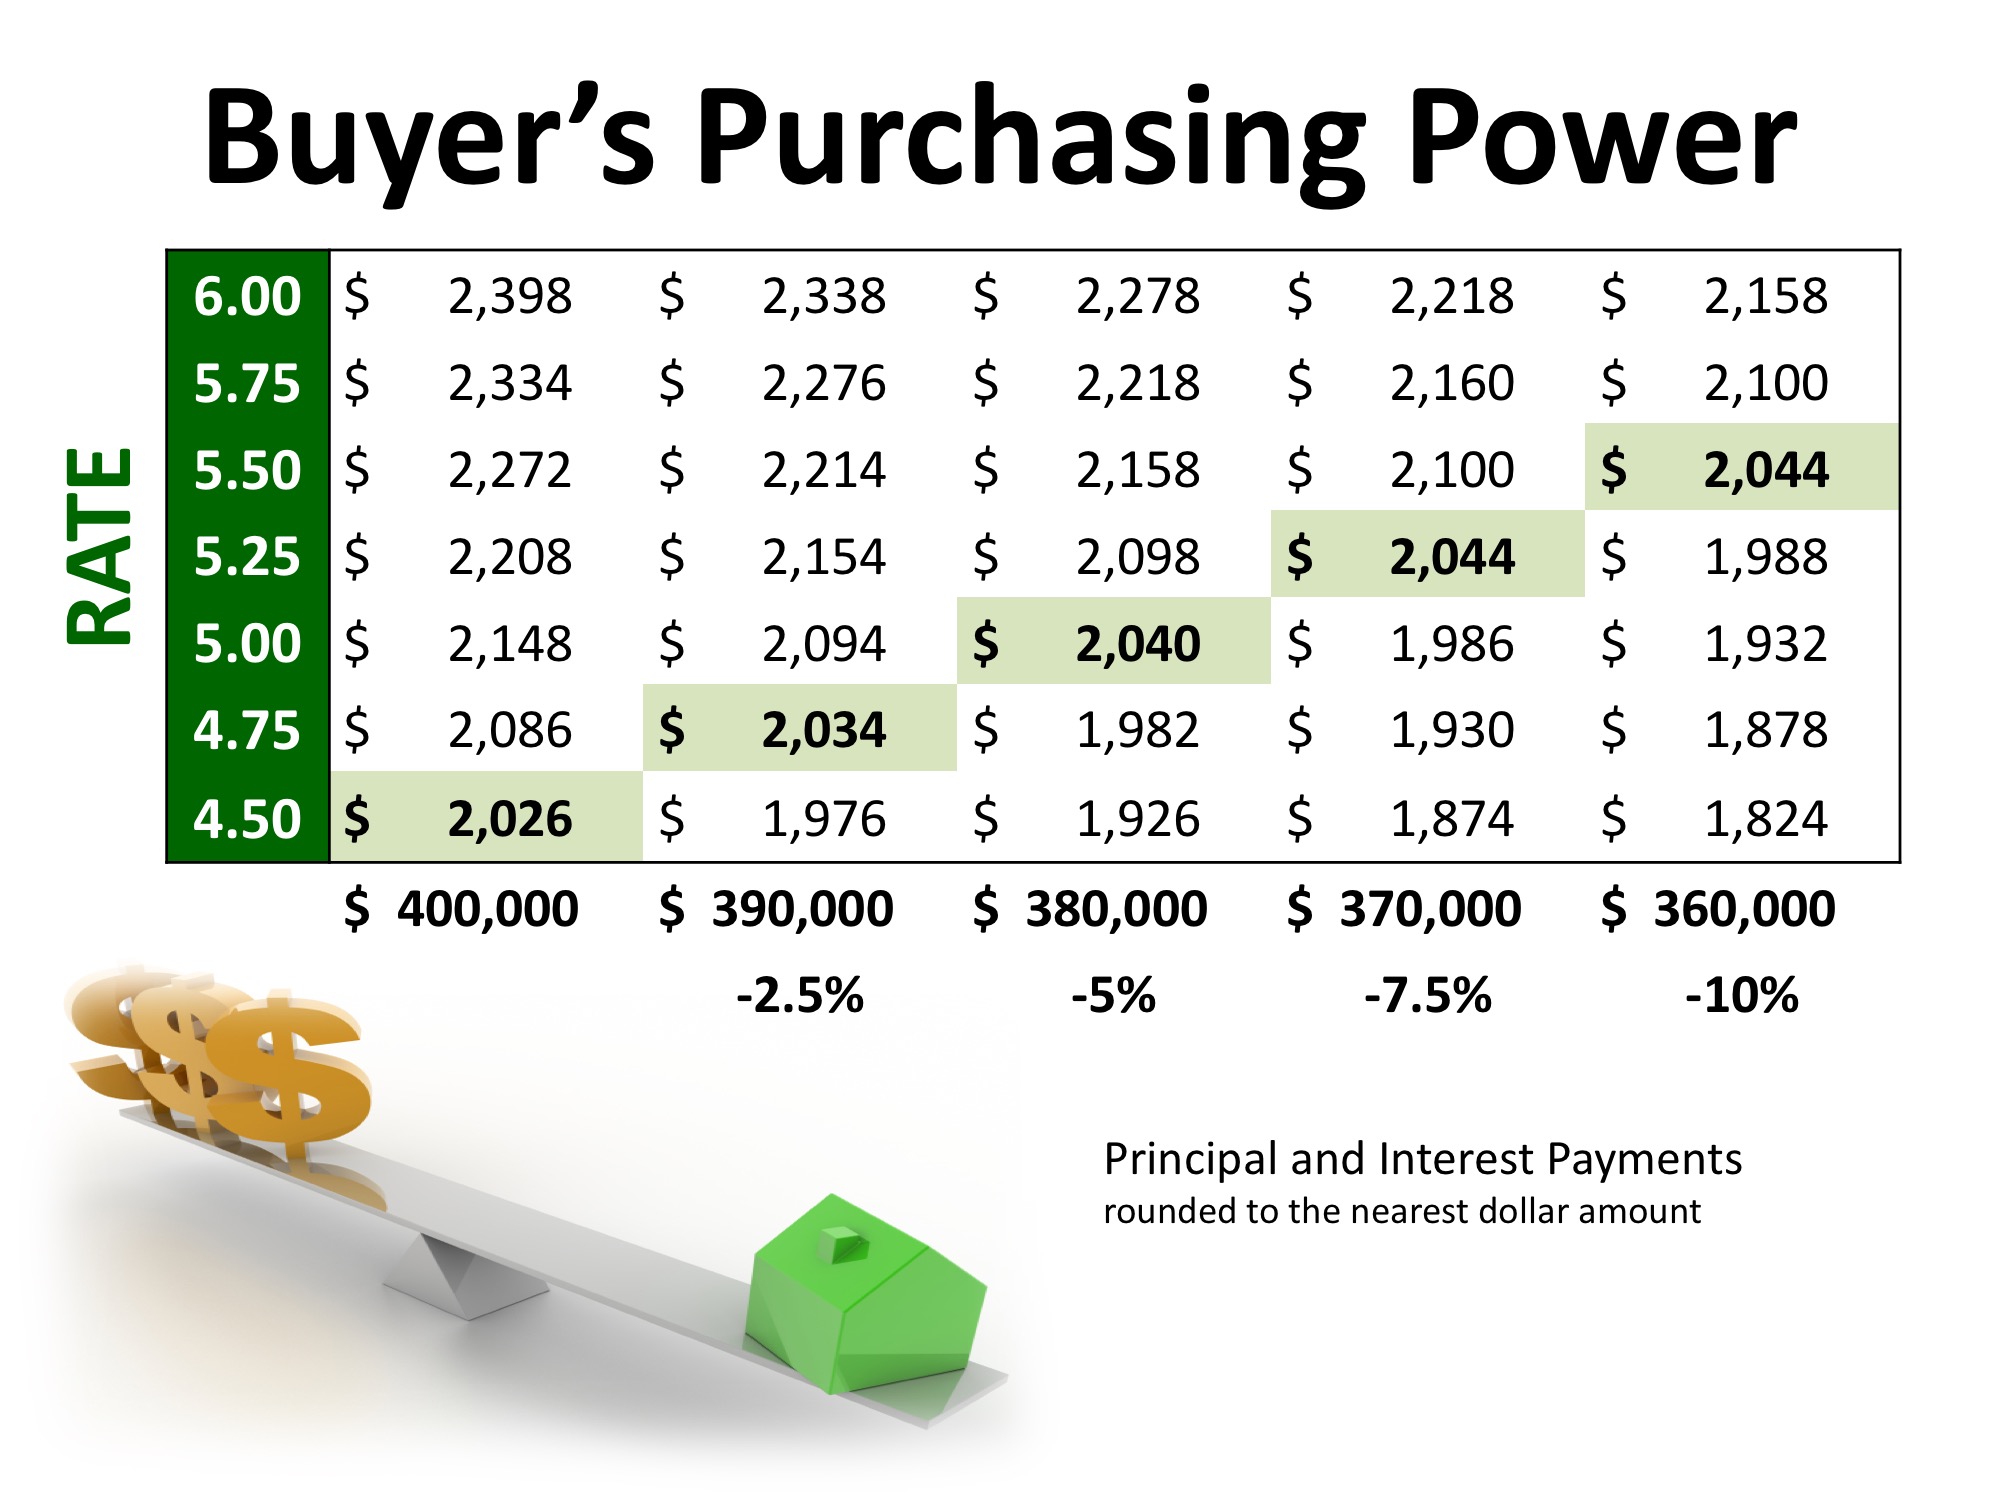
Purchasing power, simply put, is the amount of home you can afford to buy for the budget you have available to spend. As rates increase, the price of the house you can afford to buy will decrease if you plan to stay within a certain monthly housing budget.

The chart below shows the impact that rising interest rates would have if you planned to purchase a $400,000 home while keeping your principal and interest payments between $2,020-$2,050 a month.


With each quarter of a percent increase in interest rate, the value of the home you can afford decreases by 2.5% (in this example, $10,000). Experts predict that mortgage rates will be over 5% by this time next year.


Inventory


A ‘normal’ real estate market requires there to be a 6-month supply of homes for sale in order for prices to increase only with inflation. According to the National Association of Realtors (NAR), listing inventory is currently at a 4.3-month supply (still well below the 6-months needed), which has put upward pressure on home prices. Home prices have increased year-over-year for the last 78 straight months.

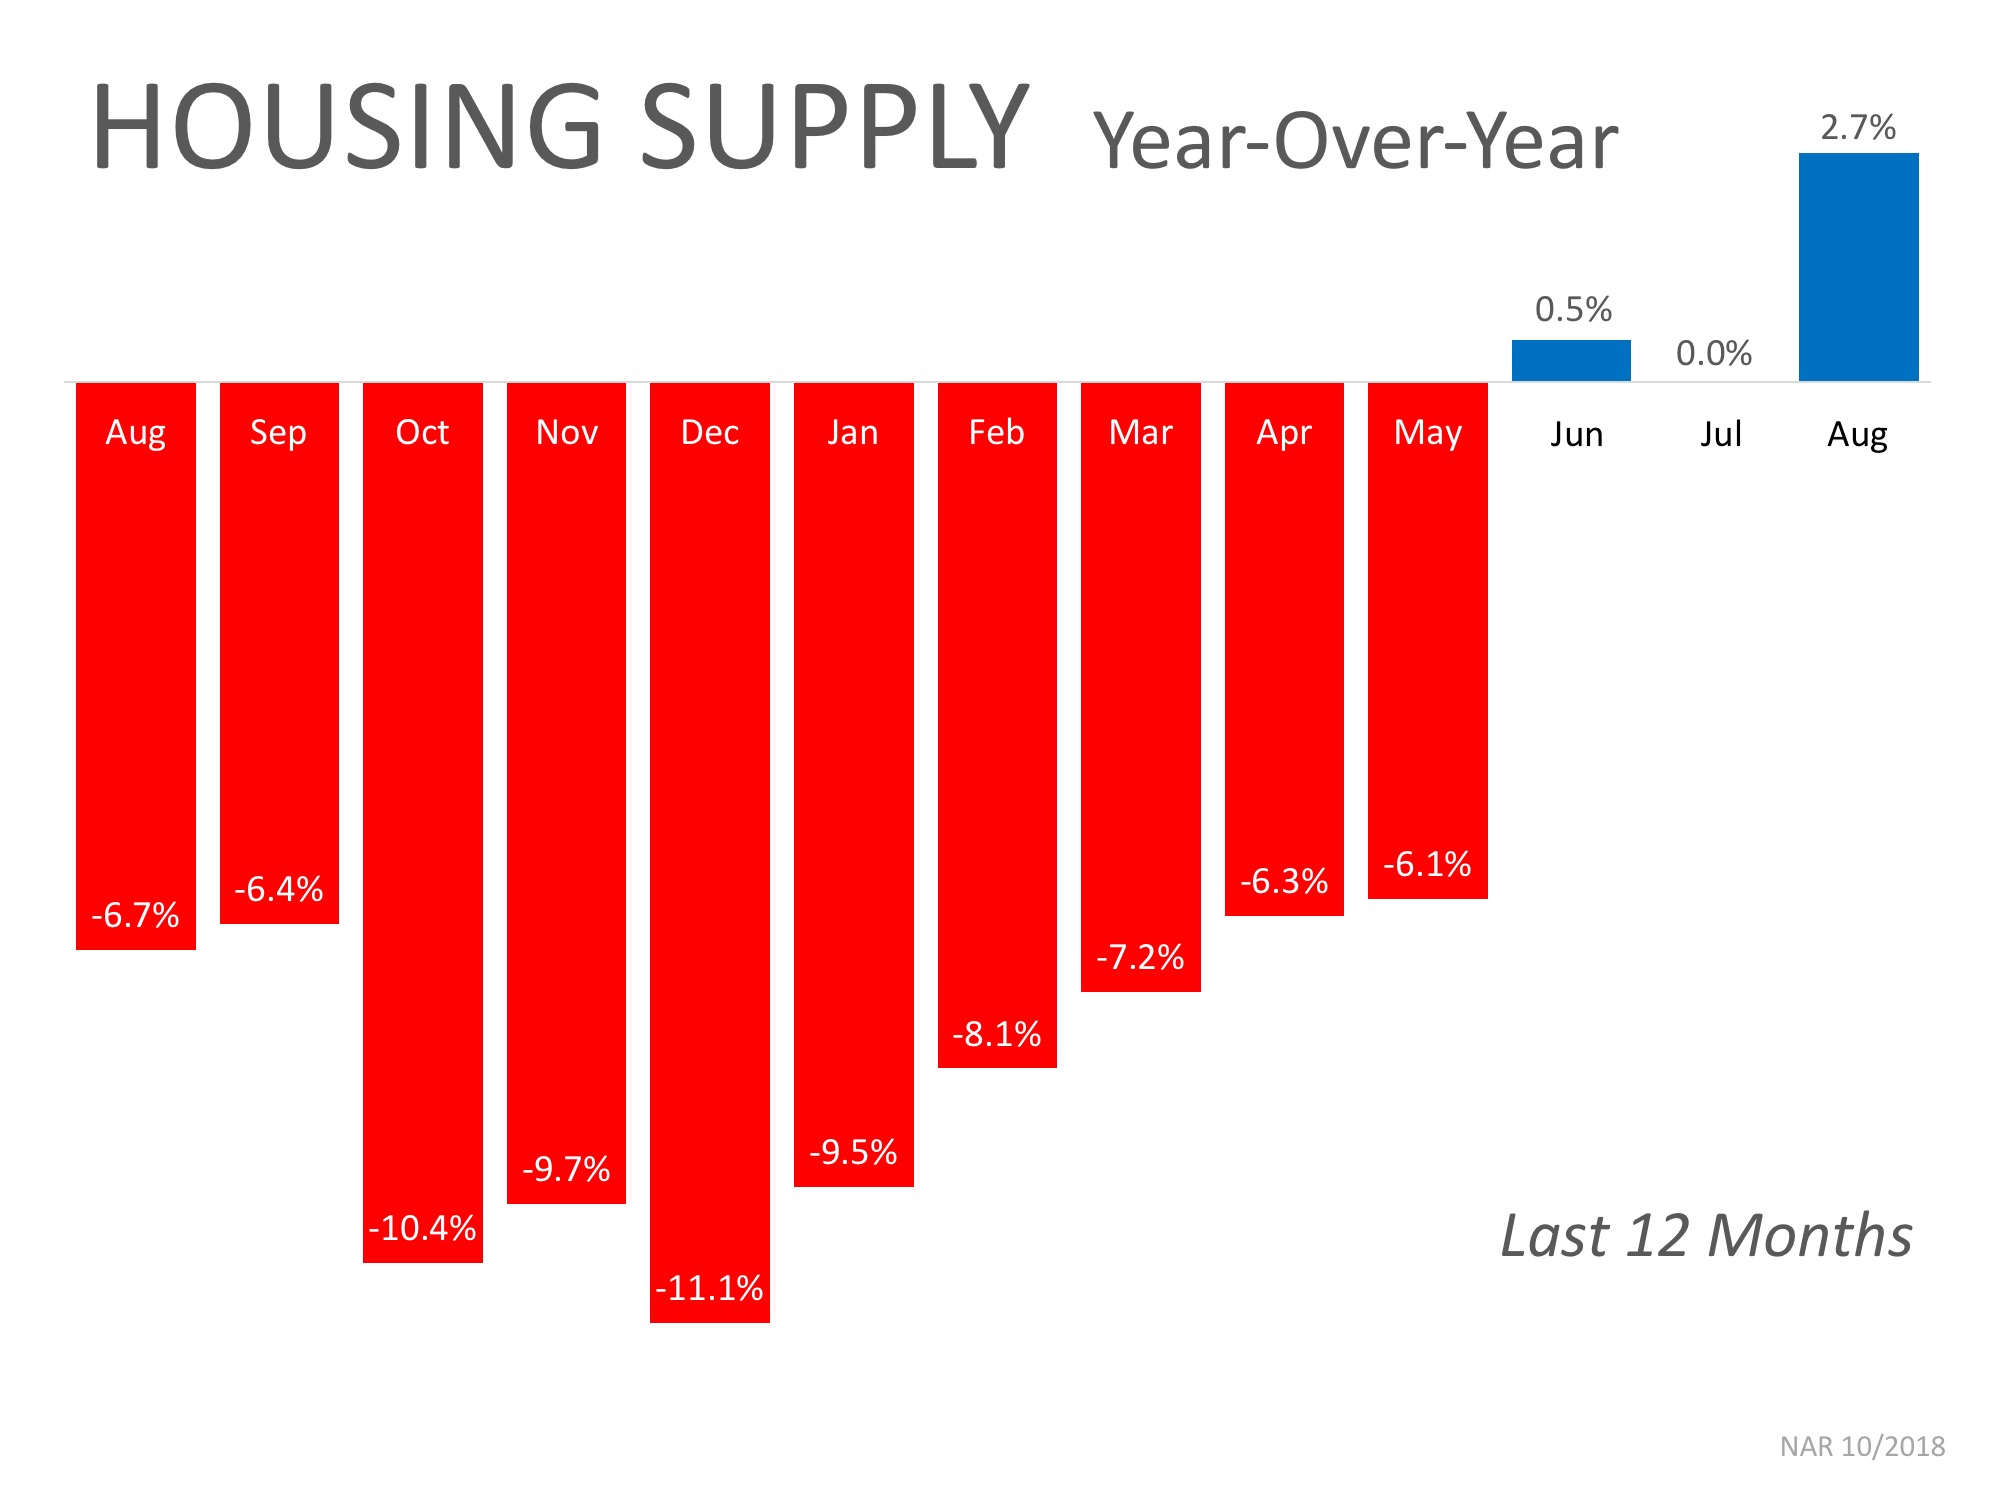
The inventory of homes for sale in the real estate market had been on a steady decline and experienced year-over-year drops for 36 straight months (from July 2015 to May 2018), but we are starting to see a shift in inventory over the last three months.

The chart below shows the change in housing supply over the last 12 months compared to the previous 12 months. As you can see, in June, July, and August, inventory levels have started to increase as compared to the same time last year.


This is a trend to watch as we move further into the fall and winter months. If we continue to see an increase in homes for sale, we could start moving further away from a seller’s market and closer to a normal market.


Bottom Line

If you are planning to enter the housing market, either as a buyer or a seller, let’s get together to discuss the changes in mortgage interest rates and inventory and what they could mean for you.

Looking to Buy, Sell, or Invest? Contact:

David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 & 2017 Recognition of Excellence Award Winner SDAR

Wednesday, June 7, 2017

5 Reasons You Should Sell This Summer


Here are five reasons listing your home for sale this summer makes sense.


1. Demand Is Strong

The latest Buyer Traffic Report from the National Association of Realtors (NAR) shows that buyer demand remains very strong throughout the vast majority of the country. These buyers are ready, willing and able to purchase… and are in the market right now! More often than not, multiple buyers are competing with each other to buy a home.

Take advantage of the buyer activity currently in the market.

2. There Is Less Competition Now

Housing inventory is currently at a 4.2-month supply, well under the 6-months needed for a normal housing market. This means, in the majority of the country, there are not enough homes for sale to satisfy the number of buyers in that market. This is good news for home prices. However, additional inventory could be coming to the market soon.

There is a pent-up desire for many homeowners to move, as they were unable to sell over the last few years because of a negative equity situation. Homeowners are now seeing a return to positive equity as real estate values have increased over the last two years. Many of these homes will be coming to the market this summer.

Also, builder's confidence in the market has hit its highest mark in over 11 years. Experts are predicting that new construction of single-family homes will ramp up this summer.

The choices buyers have will continue to increase. Don’t wait until all this other inventory of homes comes to market before you sell.

3. The Process Will Be Quicker

Fannie Mae anticipates an acceleration in home sales that will surpass 2007's pace. As the market continues to strengthen, banks will be inundated with loan inquiries causing closing-time lines to lengthen. Selling now will make the process quicker & simpler. According to Ellie Mae’s latest Origination Insights Report, the time to close a loan has dropped to a new low of 42 days, after seeing a 12-month high of 48 days in January.

4. There Will Never Be a Better Time to Move Up

If you are moving up to a larger, more expensive home, consider doing it now. Prices are projected to appreciate by 4.9% over the next year, according to CoreLogic. If you are moving to a higher-priced home, it will wind up costing you more in raw dollars (both in down payment and mortgage payment) if you wait.

You can also lock in your 30-year housing expense with an interest rate around 4% right now. Rates are projected to increase in the next 12 months.

5. It’s Time to Move on with Your Life

Look at the reason you decided to sell in the first place and determine whether it is worth waiting. Is money more important than being with family? Is money more important than your health? Is money more important than having the freedom to go on with your life the way you think you should?

Only you know the answers to the questions above. You have the power to take control of the situation by putting your home on the market. Perhaps the time has come for you and your family to move on and start living the life you desire.

That is what is truly important

Looking to Buy, Sell, or Invest? Contact:

David Demangos - Keller Williams Realty
Cell: 858.232.8410 | Realtor® BRE# 01905183
www.AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

San Diego Real Estate Expert | Global Property Specialist
Certified Luxury Marketing Specialist | CLHMS Million Dollar Guild Agent
Green Specialist | Certified International Property Specialist
2016 Recognition of Excellence Award Winner SDAR
Saturday, November 26, 2016

You Can Never Have TMI about PMI


When it comes to buying a home, whether it is your first time or your fifth, it is always important to know all the facts. With the large number of mortgage programs available that allow buyers to purchase a home with a down payment below 20%, you can never have Too Much Information (TMI) about Private Mortgage Insurance (PMI).

What is Private Mortgage Insurance (PMI)?

Freddie Mac defines PMI as:
“An insurance policy that protects the lender if you are unable to pay your mortgage. It's a monthly fee, rolled into your mortgage payment, that is required for all conforming, conventional loans that have down payments less than 20%.
Once you've built equity of 20% in your home, you can cancel your PMI and remove that expense from your mortgage payment.”
As the borrower, you pay the monthly premiums for the insurance policy, and the lender is the beneficiary. Freddie Mac goes on to explain that:
“The cost of PMI varies based on your loan-to-value ratio – the amount you owe on your mortgage compared to its value – and credit score, but you can expect to pay between $30 and $70 per month for every $100,000 borrowed.” 
According to the National Association of Realtors, the average down payment for all buyers last year was 10%. For first-time buyers, that number dropped to 6%, while repeat buyers put down 14% (no doubt aided by the sale of their home). This just goes to show that for a large number of buyers last year, PMI did not stop them from buying their dream homes.
Here’s an example of the cost of a mortgage on a $200,000 home with a 5% down payment & PMI, compared to a 20% down payment without PMI:
You Can Never Have TMI about PMI | MyKCM

The larger the down payment you can make, the lower your monthly housing cost will be, but Freddie Mac urges you to remember:
“It's no doubt an added cost, but it's enabling you to buy now and begin building equity versus waiting 5 to 10 years to build enough savings for a 20% down payment.”

Bottom Line

If you have questions about whether you should buy now or wait until you’ve saved a larger down payment, let’s get together to discuss our market’s conditions and to help you make the best decision for you and your family.


Looking to Buy, Sell, or Invest? Contact:

David Demangos
Cell: 858.232.8410
www.AwesomeSanDiegoRealEstate.com
David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Sunday, November 20, 2016

From Empty Nest to Full House, Multigenerational Families Are Back!


Multi-generational homes are coming back in a big way! In the 1950s, about 21%, or 32.2 million Americans shared a roof with their grown children or parents. According to a recent Pew Research Center report, the number of multi-generational homes dropped to as low as 12% in 1980 but has shot back up to 19%, roughly 60.6 million people, as recently as 2014.
Multi-generational households typically occur when adult children (over the age of 25) either choose to, or need to, remain living in their parent’s home, and then have children of their own. These households also occur when grandparents join their adult children and grandchildren in their home.
According to the National Association of Realtors’ (NAR) 2016 Profile of Home Buyers and Sellers, 11% of home buyers purchased multi-generational homes last year. The top 3 reasons for purchasing this type of home were:
  • To take care of aging parents (19%)
  • Cost savings (18%, up from 15% last year)
  • Children over the age of 18 moving back home (14%, up from 11% last year)
Donna Butts, Executive Director of Generations United, points out that,
“As the face of America is changing, so are family structures. It shouldn’t be a taboo or looked down upon if grown children are living with their families or older adults are living with their grown children.”
For a long time, nuclear families (a couple and their dependent children) became the accepted norm, but John Graham, co-author of “Together Again: A Creative Guide to Successful Multi-generational Living,” says, “We’re getting back to the way human beings have always lived in – extended families.”
This shift can be attributed to several social changes over the decades. Growing racial and ethnic diversity in the U.S. population helps explain some of the rise in multi-generational living. The Asian and Hispanic populations are more likely to live in multi-generational family households and these two groups are growing rapidly.
Additionally, women are a bit more likely to live in multi generational conditions than are their male counterparts (20% vs. 18%, respectively). Last but not least, basic economics.
Carmen Multhauf, co-author of the book “Generational Housing: Myth or Mastery for Real Estate,” brings to light the fact that rents and home prices have been skyrocketing in recent years. She says that, “The younger generations have not been able to save,” and often struggle to get good-paying jobs.

Bottom Line

Multigenerational households are making a comeback. While it is a shift from the more common nuclear home, these households might be the answer that many families are looking for as home prices continue to rise in response to a lack of housing inventory.

Looking to Buy, Sell, or Invest? Contact:

David Demangos
Cell: 858.232.8410
www.AwesomeSanDiegoRealEstate.com
David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Saturday, October 29, 2016

Buying a Home Can Be Scary... Know the Facts


Some Highlights:


  • 36% of Americans think they need a 20% down payment to buy a home.
  • 44% of Millennials who purchased a home this year have put down less than 10%.
  • 71.8% of loan applications were approved last month.
  • The average credit score of approved loans was 731 in September.

Looking to Buy, Sell, or Invest? Contact:

David Demangos
Cell: 858.232.8410
www.AwesomeSanDiegoRealEstate.com
David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Don't Disqualify Yourself... Over Half of All Loans Approved Have a FICO Score Under 750

The results of countless studies have shown that potential home buyers, and even current homeowners, have an inflated view of what is really required to qualify for a mortgage in today’s market.

One such study by the Wharton School of Business at the University of Pennsylvania, revealed that many Millennials have not yet considered purchasing a home, simply because they don’t believe they can qualify for a mortgage.

The article quoted Jessica Lautz, the National Association of Realtors’ Managing Director of Survey Research, as saying that there is a significant population that does not think they will be approved for a mortgage and doesn’t even try. The article also quotedFannie Mae CEO Tim Mayopoulos:

“I do think that there’s a sense out there in the marketplace among borrowers that credit may not be available, especially for people with lower credit scores.”

Ellie Mae’s Vice President, Jonas Moe recently encouraged buyers to know their options before assuming that they do not qualify for a mortgage:

“Many potential home buyers are 'disqualifying' themselves. You don't need a 750 FICO Score and a 20% down payment to buy.”

So what credit score is necessary?

Below is a breakdown of the FICO Score Distribution of all closed (approved) loans in August from Ellie Mae’s latest Origination Report.

Over 50% of all approved loans had a FICO Score under 750. Many potential home buyers believe that they need a score over 780 to qualify.

Bottom Line

If owning a home of your own has always been a dream of yours and you are ready and willing to buy, find out if you are able to! Let’s get together to determine if your dreams can become a reality sooner than you thought!


Looking to Buy, Sell, or Invest? Contact:

David Demangos
Cell: 858.232.8410
www.AwesomeSanDiegoRealEstate.com
David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Wednesday, October 26, 2016

Appraisers & Homeowners Don't See Eye-To-Eye on Values

In today’s housing market, where supply is very low and demand is very high, home values are increasing rapidly. Many experts are projecting that home values could appreciate by another 5%+ over the next twelve months. One major challenge in such a market is the bank appraisal.

If prices are surging, it is difficult for appraisers to find adequate, comparable sales (similar houses in the neighborhood that closed recently) to defend the selling price when performing the appraisal for the bank.

Every month, Quicken Loans measures the disparity between what a homeowner believes their house is worth as compared to an appraiser’s evaluation in their Home Price Perception Index (HPPI). Here is a chart showing that difference for each of the last 12 months.


Bottom Line
Every house on the market has to be sold twice; once to a prospective buyer and then to the bank (through the bank’s appraisal). With escalating prices, the second sale might be even more difficult than the first. If you are planning on entering the housing market this year, let’s get together to discuss this, and any other obstacle that may arise.


Looking to Buy, Sell, or Invest? Contact:
David Demangos
Cell: 858.232.8410
www.AwesomeSanDiegoRealEstate.com
David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Sunday, September 18, 2016

Is the Current Pace of Home Sales Sustainable?


There are some experts questioning whether the current pace of residential home sales is sustainable. Are too many people buying homes like in 2004-2006? Are we headed for another housing crisis? Actually, if we look closely at the numbers, we can see that we are looking at a very healthy real estate market.

Why the concern?

Some are looking at the last three years of home sales and comparing them to the three years just prior to the housing bubble. Looking at the graph below, we can understand that thinking.

However, if we go further back in history, we can see the real picture. After taking out the “boom; bust” years, the pace of sales is growing at a quite natural pace.

And new home sales are way below historic numbers. Trulia’s Chief Economist Ralph McLaughlin explains:
“Adjusted for population, [new home sales] are at about 63% of their fifty-year average level—way better than 2011, but nowhere near heated.”

Bottom Line

The current pace of residential home sales definitely seems sustainable.


Looking to Buy, Sell, or Invest? Contact:

David Demangos
858.232.8410
Locally Known, Globally Connected
Luxury Home Marketing Specialist
Global Property Specialist

David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Saturday, September 3, 2016

How Do Rising Prices Impact Your Home Equity?

Recently, we shared the results of the latest Home Price Expectation Survey byPulsenomics. One of the big takeaways from the survey is that over the next five years, home prices will appreciate 3.5% per year on average, and cumulatively will grow by around 18%.

So what does this mean for homeowners and their equity position?

For example, let’s assume a young couple purchased and closed on a $250,000 home in January of this year. If we only look at the projected increase in the price of that home, how much equity would they earn over the next 5 years?

Since the experts predict that home prices will increase by 4.5% this year alone, the young homeowners will have gained over $11,000 in equity in just one year.
Over a five-year period, their equity will increase by over $46,000! This figure does not even take into account their monthly principal mortgage payments. In many cases, home equity is one of the largest portions of a family’s overall net worth.

Bottom Line

Not only is homeownership something to be proud of, it also offers you and your family the ability to build equity you can borrow against in the future. If you are ready and willing to buy, find out if you are able to today!

Looking to Buy, Sell, or Invest? Contact:

David Demangos
858.232.8410
Locally Known, Globally Connected
Luxury Home Marketing Specialist
Global Property Specialist

David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!

Tuesday, August 23, 2016

Where Are Home Prices Headed Over the Next 5 Years?

Today, many real estate conversations center on housing prices and where they may be headed. That is why we like the Home Price Expectation Survey.
Every quarter, Pulsenomics surveys a nationwide panel of over one hundred economists, real estate experts, and investment & market strategists about where they believe prices are headed over the next five years. They then average the projections of all 100+ experts into a single number.

The results of their latest survey:

Home values will appreciate by 4.5% over the course of 2016, 3.6% in 2017 and about 3.2% in the next two years, and finally 2.9% in 2020 (as shown below). That means the average annual appreciation will be 3.5% over the next 5 years.
The prediction for cumulative appreciation increased over a full point from 17.5% to 18.7% by 2020. The experts making up the most bearish quartile of the survey are still projecting a cumulative appreciation of 11.1%.

Bottom Line

Individual opinions make headlines. We believe the survey is a fairer depiction of future values.
Looking to Buy, Sell, or Invest? Contact:

David Demangos
858.232.8410
Locally Known, Globally Connected
Luxury Home Marketing Specialist
Global Property Specialist

David@AwesomeSanDiegoRealEstate.com
Our Team Goes to Extremes to Fulfill Your Real Estate Dreams!